

Refinance or renew? How to choose when mortgage renewal creates sticker shock
Advertisement
Read this article for free:
or
Already have an account? Log in here »
To continue reading, please subscribe:
Digital Subscription
One year of digital access for only $205*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*First annual payment billed as $205.00 + GST for one year. This annual subscription will automatically renew at $233.00 + GST every 52 weeks (10% off the regular annual price of $259.35). Offer available to new and qualified returning subscribers only. Cancel any time.
To continue reading, please subscribe:
Add Free Press access to your Brandon Sun subscription for only an additional
$1 for the first 4 weeks*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*Your next Brandon Sun subscription payment will increase by $1.00 and you will be charged $17.95 plus GST for four weeks. After four weeks, your payment will increase to $24.95 plus GST every four weeks.
Read unlimited articles for free today:
or
Already have an account? Log in here »
Hey there, time traveller!
This article was published 23/10/2023 (1060 days ago), so information in it may no longer be current.
MONTREAL – Many Canadian homeowners are facing sticker shock with their monthly payments as their mortgage comes up for renewal, leaving them with a crucial choice: whether to renew or refinance their home loan.
“They’re used to paying $2,000 every single month for the last five years and all of a sudden, now their payments are going to go up to $4,000,” said Leah Zlatkin, a mortgage expert at LowestRates.ca.
When a homeowner renews an existing mortgage at the end of its term, traditionally five years, the lender updates the contract with a new interest rate — and as Zlatkin says, most mortgage-holders will see higher monthly payments after a swiftstring of increases to the Bank of Canada’s key rate.
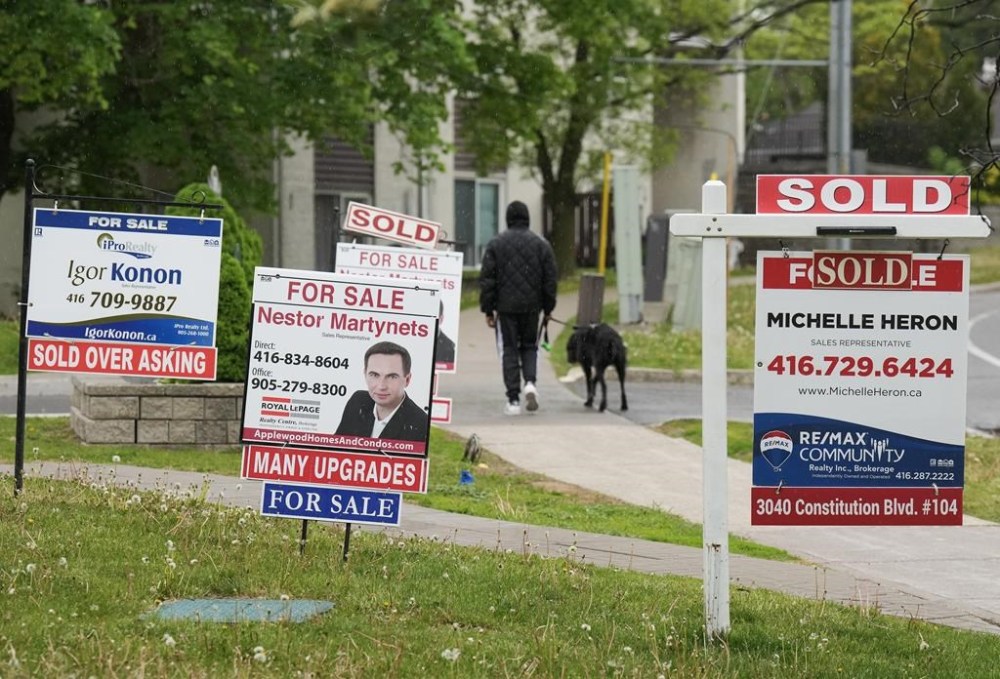
Refinancing involves breaking the current contract entirely and signing a fresh one. It’s a useful option for those looking to access home equity, consolidate debt or switch lenders for a better rate. It also allows the borrower to extend their amortization period, or the length of time to fully pay off the mortgage.
For those with thinner wallets, “you’re refinancing in order to re-amortize to a longer period of time to ease those payments,” Zlatkin said.
The result may be more total interest paid in the long term, but the monthly costs are lower, since the payments are stretched over several more years.
Research from the Bank of Canada shows nearly half of Canadian mortgages had amortizations longer than 25 years as of June 30. The proportion has been climbing steadily from 32 per cent in the summer of 2020.
Borrowers whose mortgage rates have soared to the point that their monthly payments barely cover the interest portion — or fail to do even that — might consider a lump-sum payment if they’re fortunate enough to have some spare cash on hand.
“There’s been a high number of customers liquidating some of those savings that they have and putting it toward their mortgage,” said Nick Palucci, senior director of client strategy at the Royal Bank of Canada.
Those on the hunt for a better rate than the one offered by their lender can seek the help of a mortgage broker.
Renewal is the more typical route, and makes sense “as long as you’re offered a favourable rate,” according to Zlatkin.
“Your bank is going to give you their best rate. They’re not necessarily going to give you the best rate on the market,” Zlatkin said, adding that bargaining might be best left to the pros.
“Realistically, the only way the lender is going to play ball with you is if you have an offer from somebody else.”
Homeowners that opt to refinance should keep in mind it can come with legal and appraisal fees, while doing so before the mortgage term ends comes with a penalty.
They should be aware that refinancing also means they’ll have to pass the federal government’s mortgage stress test by proving they could still afford the loan if the interest rate went up by two percentage points.
Data from the Canada Mortgage and Housing Corp. in May showed the number of refinances fell by nearly a third from May 2022.
“It’s really important to sit down with a professional financial planner who can gather in all your assets, your debt … savings, your income flow, what your burn rate is. It can help you to move the shells around to optimize your situation,” said Mark Halpern, who runs WealthInsurance.com.
Another reasonto refinance may simply come down to user experience.
“It could be something as small as, you’re having a difficult time logging in and just seeing how much principal is remaining on your mortgage, you’re having a difficult time seeing what your balances are,” Zlatkin said.
“Maybe you didn’t have a home equity line of credit … because your lender didn’t allow you to do a home equity line of credit, and you had to use your credit cards. So now you feel you have to refinance.”
For some, another time-tested, albeit fraught, refinancing option may be tempting.

“My favourite strategy: good friends and good family,” Halpern said.
“Auntie Sally or uncle Bob, they’re doing extremely well. Why not arrange a little private mortgage with them? They’re not going to gouge you,” he said.
“They love you and want to make sure that you’re OK, and then you can work out some sort of payment schedule with them that is not as onerous.”
For those not blessed with a wealthy, generous parent or relative — or unwilling to attach financial strings to them — a more commercial path to shouldering that mortgage may be the only one open.
This report by The Canadian Press was first published Oct. 23, 2023.
Related Articles
Macklem warns premiers against interference in BoC
Advertisement Advertise With Us
Advertisement Advertise With Us