Buy Now, Pay Later loans will soon affect some credit scores
Advertisement
Read this article for free:
or
Already have an account? Log in here »
To continue reading, please subscribe:
Digital Subscription
One year of digital access for only $205*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*First annual payment billed as $205.00 + GST for one year. This annual subscription will automatically renew at $233.00 + GST every 52 weeks (10% off the regular annual price of $259.35). Offer available to new and qualified returning subscribers only. Cancel any time.
To continue reading, please subscribe:
Add Free Press access to your Brandon Sun subscription for only an additional
$1 for the first 4 weeks*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*Your next Brandon Sun subscription payment will increase by $1.00 and you will be charged $17.95 plus GST for four weeks. After four weeks, your payment will increase to $24.95 plus GST every four weeks.
Read unlimited articles for free today:
or
Already have an account? Log in here »
Hey there, time traveller!
This article was published 26/06/2025 (446 days ago), so information in it may no longer be current.
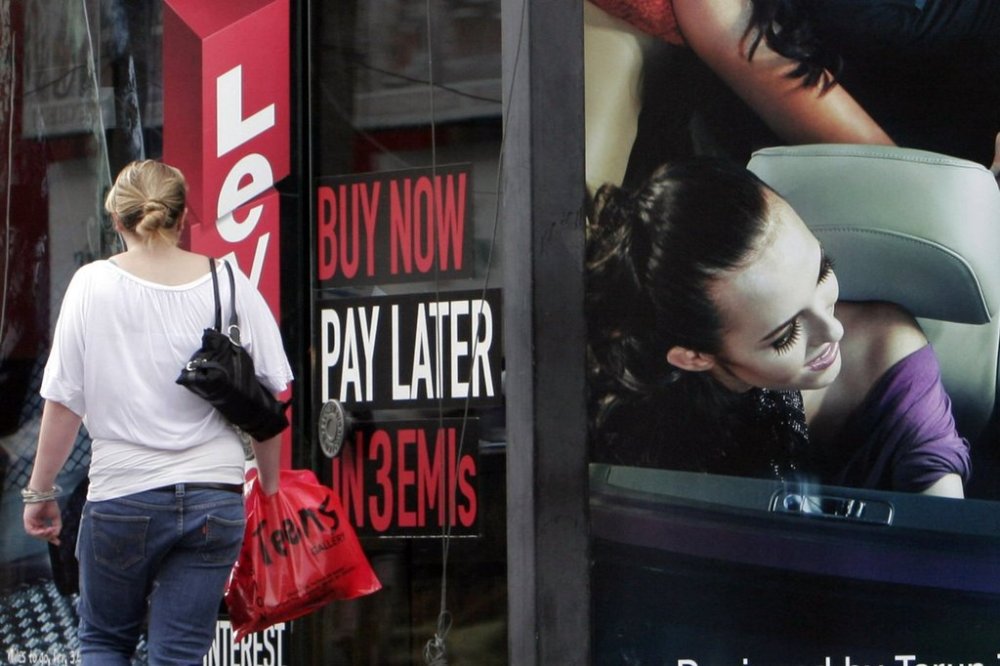
NEW YORK (AP) — Hundreds of millions of ‘Buy Now, Pay Later’ loans will soon affect credit scores for millions of Americans who use the loans to buy clothing, furniture, concert tickets, and takeout.
Scoring company FICO said Monday that it is rolling out a new model that factors the short-term loans into their consumer scores. A majority of lenders use FICO scores to determine a borrower’s credit worthiness. Previously, the loans had been excluded, though Buy Now, Pay Later company Affirm began voluntarily reporting pay-in-four loans to Experian, a separate credit bureau, in April.
The new FICO scores will be available beginning in the fall, as an option for lenders to increase visibility into consumers’ repayment behavior, the company said. Still, not all Buy Now, Pay Later companies share their data with the credit bureaus, and not all lenders will opt in to using the new models, so widespread adoption could take time, according to Adam Rust, director of financial services at the nonprofit Consumer Federation of America.
Here’s what to know.
Why haven’t the loans appeared in credit scores previously?
Typically, when using Buy Now, Pay Later loans, consumers pay for a given purchase in four installments over six weeks, in a model more similar to layaway than to a traditional credit card. The loans are marketed as zero-interest, and most require no credit check or only a soft credit check.
The main three credit reporting bureaus, Experian, TransUnion, and Equifax, haven’t yet incorporated a standard way of including these new financial products in their reports, since they don’t adhere to existing models of lending and repayment. FICO, the score of the Fair Isaac Corporation, uses data from the bureaus to calculate its own credit score, and is independently choosing to pilot a new score that takes the loans into account.
Why is this important?
BNPL providers promote the plans as safer alternatives to credit cards, while consumer advocates warn about “loan stacking,” in which consumers take on many loans at once across several companies. So far, there’s been little visibility into this practice in the industry, and the opacity has led to warnings of “phantom debt” that could mask the health of the consumer.
In a statement, FICO said that their new credit score model is accounting for the growing significance of the loans in the U.S. credit ecosystem.
“Buy Now, Pay Later loans are playing an increasingly important role in consumers’ financial lives,” said Julie May, vice president and general manager of business-to-business scores at FICO. “We’re enabling lenders to more accurately evaluate credit readiness, especially for consumers whose first credit experience is through BNPL products.”
What does FICO hope to achieve?
FICO said the new model will responsibly expand access to credit. Many users of BNPL loans are younger consumers and consumers who may not have good or lengthy credit histories. In a joint study with Affirm, FICO trained its new scores on a sample of more than 500,000 BNPL borrowers and found that consumers with five or more loans typically saw their scores increase or remain stable under the new model.
For consumers who pay back their BNPL loans in a timely way, the new credit scoring model could help them improve their credit scores, increasing access to mortgages, car loans, and apartment rentals. Currently, the loans don’t typically contribute directly to improved scores, though missed payments can hurt or ding a score.
Since March, credit scores have declined steeply for millions, as student loan payments resume and many student borrowers find themselves unable to make regular payments on their federal student loans.
What are the risks and concerns?
Nadine Chabrier, senior policy and litigation counsel at the Center for Responsible Lending, said her main concern is that the integration of the loans into a score could have unexpected negative effects on people who are already credit-restrained.
“There isn’t a lot of information out there about how integrating BNPL into credit scoring will work out,” Chabrier said. “FICO simulated the effect on credit scoring through a study. They saw that some users’ scores increased. But if you factor in something that, last week, didn’t affect your credit, and this week, it does, without having very much information about the modeling, it’s a little hard to tell what the consequences will be.”
Chabrier cited research that’s shown that many BNPL users have revolving credit card balances, lower credit scores, delinquencies, and existing debt. Women of color are also more likely to use the loans, she said.
“This is a credit vulnerable community,” said Chabrier.
Will consumers see immediate effects?
Rust, of the Consumer Federation of America, said he doesn’t expect this to be a game-changer for consumers who already have a credit profile.
“Are we at a point where using BNPL loans will dramatically alter your credit profile? Probably not,” he said. “I think it’s important that people have reasonable expectations.”
Rust said the average BNPL loan is for $135, and that repaying such small loans, even consistently, might not result in changes to a credit score that would significantly move the needle.
“It’s not about going from 620 to 624. It’s about going from 620 to 780,” he said, referring to the kind of credit score jumps that affect one’s credit card offers, interest rates on loans, and the like.
Still, Rust said that increased transparency around the loans could create a more accurate picture of a consumer’s debts, which could improve accurate underwriting and keep consumers from over-extending themselves.
“This addresses the problem of ‘phantom debt,’ and that’s a good thing,” he said. “Because it could be something that keeps people from getting too deeply into debt they can’t afford.”
___
The Associated Press receives support from Charles Schwab Foundation for educational and explanatory reporting to improve financial literacy. The independent foundation is separate from Charles Schwab and Co. Inc. The AP is solely responsible for its journalism.