Flood insurance costs rise in areas once deemed lower risk
Advertisement
Read this article for free:
or
Already have an account? Log in here »
To continue reading, please subscribe:

Digital Subscription
One year of digital access for only $205*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*First annual payment billed as $205.00 + GST for one year. This annual subscription will automatically renew at $233.00 + GST every 52 weeks (10% off the regular annual price of $259.35). Offer available to new and qualified returning subscribers only. Cancel any time.
To continue reading, please subscribe:
Add Free Press access to your Brandon Sun subscription for only an additional
$1 for the first 4 weeks*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*Your next Brandon Sun subscription payment will increase by $1.00 and you will be charged $17.95 plus GST for four weeks. After four weeks, your payment will increase to $24.95 plus GST every four weeks.
Read unlimited articles for free today:
or
Already have an account? Log in here »
Hey there, time traveller!
This article was published 08/12/2021 (1756 days ago), so information in it may no longer be current.
WASHINGTON (AP) — In the past year, the southwestern Louisiana city of Lake Charles weathered two hurricanes, intense rainfall that sent water gushing down streets and a deep freeze that burst pipes.
Yet Tommy Eastman may eventually drop coverage on his four-bedroom home — which has so far escaped damage — because the cost of his flood insurance is going up.
“Once it starts getting over $1,000, I’m gonna start thinking, ‘Well, what am I doing?’” said Eastman, a real estate agent whose annual policy is scheduled to climb from $600 to $2,500 over the next several years.
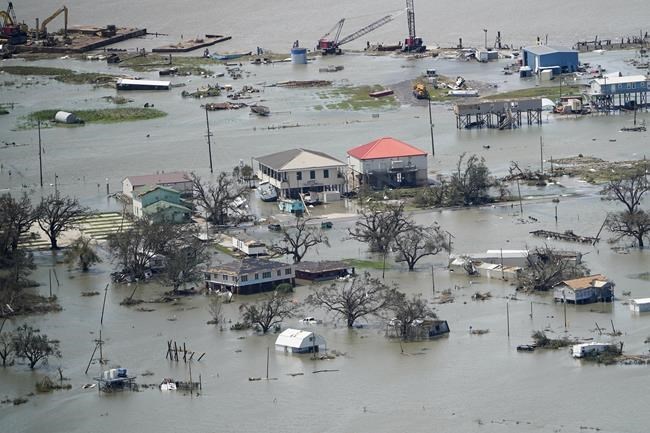
Under a revamped federal flood insurance program rolled out this fall, millions of homeowners are set for rate hikes that officials say more accurately reflect a property’s risk. That includes the vast majority of the 1.7 million homeowners with relatively cheap policies in areas federal officials previously deemed low or moderate risk — and where coverage is voluntary.
The overhaul is intended in part to make it more expensive to develop in risky areas. But some worry the price hikes will only make it harder to convince homeowners to voluntarily buy or keep flood coverage, particularly in middle- and working-class areas.
“We have no high-rise condominiums, we have no sandy white beaches. It is a working coast in our state,” said Jim Donelon, Louisiana’s insurance commissioner.
The Federal Emergency Management Agency says its new insurance program factors in the characteristics of individual properties, such as how close they are to water, how expensive they are to rebuild and whether they faces multiple types of flood risk. In many parts of the country, such risks are growing as climate change increases the strength of hurricanes and the intensity of rainstorms.
The program — Risk Rating 2.0 — will mean higher prices for about three-quarters of the 4.9 million federal flood insurance policies, and decreases for the rest. Voluntary policyholders in single-family homes will be hit particularly hard, with an estimated 90% set for hikes, according to FEMA. The agency said it plans to collect 50% more in premiums under the new program over time.
“We’ve learned that the old way of looking at risk had lots of gaps, which understated a property’s flood risk and communicated a false sense of security,” said David Maurstad, a senior executive of the National Flood Insurance Program.
In spite of identifying more flood risk across the country, the new system doesn’t change who is required to buy coverage. In areas FEMA deems highest risk — known as the 100-year flood zone — flood insurance is required on government-backed mortgages and many banks also require it for mortgages in high-risk areas. FEMA has said the flood maps aren’t meant to predict where flooding may occur, but say where coverage is required and help communities make building decisions.
In recent years, homeowners living in places where coverage isn’t required have faced losses in the billions of dollars. Between 2017 and 2019, nearly 40% of the flood claims FEMA received were for properties that fell outside zones where insurance is required, an agency representative told Congress last year.
Many properties outside the flood zones face risk “that has always been there but has never been identified,” said Matthew Eby, executive director of First Street Foundation, a research firm that produces detailed maps of flooding risks.
First Street estimates that 14.6 million properties across the U.S. are at substantial risk of flooding, far more than the number of flood policies federal government insures. A Government Accountability Office report this year recommended that the federal government update the rules on who is required to get coverage to protect more high-risk homes from flood disasters. A separate GAO report found FEMA’s flood maps do not reflect the latest climate science or key flood hazards such as heavy rainfall.
FEMA said it has not studied how the rate changes will affect voluntary take-up of flood insurance, and the agency has not publicly disclosed details on how high premiums will climb beyond the first year. A Congressional Research Service report said Risk Rating 2.0 will more accurately signal a home’s flood risk, but that the higher prices “may mean that insurance for some properties is considered unaffordable.”
Raising rates and having more people opt for coverage also matters for the financial health of FEMA’s flood insurance program, which is $20.5 billion in debt. Since its launch in 1968, many insurance experts say the program has deeply subsidized flood insurance by not charging rates that properly reflected a home’s risk. The federal government underwrites most flood insurance policies in the U.S.
For new policy holders, FEMA’s new rates took effect in October. For existing policy holders, new rates start taking effect in April. Since rate hikes are capped at 18% a year, it will take years for some to reach their new rates. Policyholders can call their insurers to get details on how their rates will change. Unlike before when broad groups of policies saw increases, Risk Rating 2.0 will adjust prices individually.
Higher rates will make flood risks clearer, and ideally encourage more homeowners to get insurance in areas where coverage is voluntary, said Joel Scata, a lawyer at the Natural Resources Defense Council, an environmental advocacy group. He said that Congress should act to address affordability for lower-income families.
Aric Pohorelsky, a Lake Charles resident, envisions another scenario. He pays $517 a year for flood insurance on a 3,700 square-foot home, but said the same policy would cost $5,000 for a new homeowner.

“If people leave in vast numbers … I don’t think it’s going to be because of Risk Rating 2.0,” he said. “I think it’ll be just because of the stress of dealing with major hurricanes.”
___
Phillis reported from St. Louis.
___
The Associated Press receives support from the Walton Family Foundation for coverage of water and environmental policy. The AP is solely responsible for all content. For all of AP’s environmental coverage, visit https://apnews.com/hub/environment