Liz Weston: Should seniors consider a reverse mortgage now?

Advertisement

Advertise with us

Reverse mortgages allow older homeowners to turn part of their home equity into tax-free cash, using a loan that doesn’t have to be paid back until they die, sell or move out.

Read this article for free:


or

Already have an account? Log in here »

To continue reading, please subscribe:

Subscribe and receive a limited-edition Free Press branded hat or tote.

Digital Subscription

One year of digital access for only $205*

  • Enjoy unlimited reading on winnipegfreepress.com
  • Read the E-Edition, our digital replica newspaper
  • Access News Break, our award-winning app
  • Play interactive puzzles

*First annual payment billed as $205.00 + GST for one year. This annual subscription will automatically renew at $233.00 + GST every 52 weeks (10% off the regular annual price of $259.35). Offer available to new and qualified returning subscribers only. Cancel any time.

To continue reading, please subscribe:

Add Free Press access to your Brandon Sun subscription for only an additional

$1 for the first 4 weeks*

  • Enjoy unlimited reading on winnipegfreepress.com
  • Read the E-Edition, our digital replica newspaper
  • Access News Break, our award-winning app
  • Play interactive puzzles
Start now

*Your next Brandon Sun subscription payment will increase by $1.00 and you will be charged $17.95 plus GST for four weeks. After four weeks, your payment will increase to $24.95 plus GST every four weeks.

Hey there, time traveller!
This article was published 18/05/2020 (2324 days ago), so information in it may no longer be current.

Reverse mortgages allow older homeowners to turn part of their home equity into tax-free cash, using a loan that doesn’t have to be paid back until they die, sell or move out.

That sounds good to a lot of seniors navigating financial fallout during the coronavirus pandemic. Stay-at-home orders may have taken away jobs needed to make ends meet, while low interest rates and a volatile stock market have endangered income from retirement savings.

A reverse mortgage could be exactly the right tool at the right time. Or it could be an expensive mistake. It’s important to understand exactly how these loans work and to explore alternatives before you commit.

FILE - This undated file photo provided by NerdWallet shows Liz Weston, a columnist for personal finance website NerdWallet.com. When stock markets are rattled by news events, it’s unsettling for any investor — but especially so for those who are retired (or nearly there). The first thing anyone with an investment portfolio should do is make sure it’s properly balanced, taking both income needs and risk tolerance into account. (NerdWallet via AP, File)

REVERSE MORTGAGE BASICS

Most reverse mortgages are Home Equity Conversion Mortgages (HECMs), which are insured by the federal government. Borrowers must be 62 or older and have substantial home equity.

The amount you can borrow not only depends on your equity and the home’s value, it also varies based on your age, current interest rates and HECM program limits. The higher your age and the lower the prevailing interest rate, the more you can typically borrow. Currently the program will let you borrow against a maximum of $765,600 in home value.

Borrowers can get a lump sum, a line of credit or a series of regular payments. Reverse mortgages can also be used to pay off an existing mortgage or to buy a home.

You don’t have to make payments on a reverse mortgage, even if you end up owing more than the house is worth. You can, however, wind up in foreclosure if you fall behind on property taxes, homeowners insurance or homeowners association fees.

REVERSE MORTGAGES AREN’T CHEAP

Most of the costs are taken from your loan proceeds, so you don’t pay them out of pocket, but it’s still an expensive way to borrow. HECM loans require a 2% upfront mortgage insurance payment, plus an additional 0.5% annual charge, on top of origination costs and lenders’ fees. Any amount you borrow, including these fees and insurance, accrues interest, which means your debt grows over time.

Many borrowers don’t realize this, or that the debt can grow to the point where they may not have anything left to borrow against in an emergency or to leave to their kids, says Barbara Jones, a senior attorney for AARP Foundation.

“They don’t quite understand what compounding interest means,” Jones says. “So they don’t have the equity in their home that they thought they did.”

LOOK ELSEWHERE FOR SHORT-TERM NEEDS

If you have a short-term need for cash, consider other options first, Jones recommends. Many low-income seniors don’t realize they qualify for the earned income tax credit, a refundable tax break that can put cash in your pocket. You also could use BenefitsCheckUp, a site run by the National Council on Aging, to see what other help you may qualify for. People of any age can ask for forbearance, or the ability to skip payments, from their mortgage company and other lenders.

Another possibility is a regular home equity loan or line of credit. This type of borrowing requires you to make payments, and lenders can freeze or lower limits on lines of credit, but the borrowing costs are much lower.

REVERSE MORTGAGES CAN BE USED AS A RELIEF VALVE

Although financial planners long considered reverse mortgages to be a last resort for struggling seniors, researchers in recent years found a potential use for more affluent people: as a relief valve to take the pressure off investments in bad markets. Tapping a reverse line of credit for income instead of selling beaten-down stocks gives investment portfolios a chance to recover along with the market. That can allow people to spend more with less risk of depleting their portfolios, says Wade Pfau, professor of retirement income at The American College of Financial Services.

A reverse mortgage also can provide monthly guaranteed income that isn’t dependent on stock market swings or a healthy labour market, says Steve Resch, vice-president of retirement strategies at Finance of America Reverse, a reverse mortgage lender. So can an income annuity, which is an insurance product that gives you a stream of payments, typically for the rest of your life, in exchange for a lump sum.

Before you proceed with either a reverse mortgage or an annuity, you’d be smart to consult a certified financial planner or other fiduciary advisor. Most people promoting these products get paid to sell them, and you’ll want to check in with an objective advisor committed to putting your interests first.

_______________

This column was provided to The Associated Press by the personal finance website NerdWallet. Liz Weston is a columnist at NerdWallet, a certified financial planner and author of “Your Credit Score.” Email: lweston@nerdwallet.com. Twitter: @lizweston.

RELATED LINKS:

NerdWallet: Reverse Mortgage: What It Is, How Seniors Use It https://bit.ly/nerdwallet-reverse-mortgage

Benefits CheckUp https://www.benefitscheckup.org/
Report Error Submit a Tip

More Stories

Liz Weston: Should seniors consider a reverse mortgage now?

Liz Weston Of Nerdwallet, The Associated Press 5 minute read Preview

Liz Weston: Should seniors consider a reverse mortgage now?

Liz Weston Of Nerdwallet, The Associated Press 5 minute read Monday, May. 18, 2020

Reverse mortgages allow older homeowners to turn part of their home equity into tax-free cash, using a loan that doesn’t have to be paid back until they die, sell or move out.

That sounds good to a lot of seniors navigating financial fallout during the coronavirus pandemic. Stay-at-home orders may have taken away jobs needed to make ends meet, while low interest rates and a volatile stock market have endangered income from retirement savings.

A reverse mortgage could be exactly the right tool at the right time. Or it could be an expensive mistake. It’s important to understand exactly how these loans work and to explore alternatives before you commit.

REVERSE MORTGAGE BASICS

Read
Monday, May. 18, 2020

Province invests $3.8M in culinary arts training facility for francophone high school students

Kelly-Anne Riess 3 minute read Preview

Province invests $3.8M in culinary arts training facility for francophone high school students

Kelly-Anne Riess 3 minute read Yesterday at 12:10 PM CDT

A new dedicated culinary arts training facility will give francophone high school students a place to learn the trade in French.

The Manitoba government announced this week that it is providing $3.8 million toward the purchase of a property at 170 Marion St. and beginning design work for its renovation.

The facility will be the first dedicated vocational education site operated by Division scolaire franco-manitobaine, and the first fully French-language culinary arts program for Grade 11 and 12 students, preparing them for work in the restaurant and service sector.

“French-language education is a fundamental part of Manitoba’s identity and strength,” Education Minister Tracy Schmidt said in a news release. “It is an exciting step that will help strengthen both the francophone community and our skilled workforce.”

Read
Yesterday at 12:10 PM CDT

Jets place two on waivers

1 minute read Yesterday at 1:12 PM CDT

The Winnipeg Jets are one step closer to being down to numbers.

On Sunday afternoon, centre Danny Zhilkin and defenceman Henry Thrun were placed on waivers.

That decision would suggest  defenceman Tyrel Bauer is in line to break camp with the NHL club for the first time in his career.

The final roster, with a maximum of 23 players, must be submitted on Monday afternoon.

Charges laid after St. Boniface hospital assault

1 minute read Yesterday at 12:40 PM CDT

A man has been charged after a serious assault at St. Boniface Hospital on Saturday.

Just after 1 a.m. Sept. 26, two men were having an argument that escalated to a physical fight in which the victim sustained serious upper-body injuries, the Winnipeg Police Service stated in a news release Sunday.

When police arrived, a 36-year-old man was being detained by security personnel. The incident didn't involve hospital staff and no one else was hurt, the release stated.

James Anthony Junior Clark, 36, was arrested and charged with assault causing bodily harm and two counts of violating a probation order.

Positive anticipation is growing about major housing developments underway in Winnipeg’s downtown

Gabrielle Piché 10 minute read Preview

Positive anticipation is growing about major housing developments underway in Winnipeg’s downtown

Gabrielle Piché 10 minute read Friday, Sep. 25, 2026

If traffic is light and the wind is down, Somia Sadiq is able to hear the roar of Winnipeg Jets fans twice: first through her window, then on TV.

From her apartment view high above downtown, she can look out at Graham Avenue’s painted pedestrian landscape, see construction cranes and hear the heavy equipment at work as massive housing projects take shape at The Forks, at what used to be Portage Place shopping centre and at the former Hudson’s Bay building.

Sadiq has lived at 300 Main for 2 1/2 years, a few steps from the city’s famous, windy and reopened-to-pedestrians Portage Avenue intersection. At 42 storeys, it’s the tallest building in Winnipeg.

She is among 18,000 downtown residents who will soon be joined by thousands of others attracted to the city’s core by the new wave of major construction projects.

Read
Friday, Sep. 25, 2026

Signs of local neo-Nazi recruiting efforts spark concern

Conrad Sweatman 7 minute read Preview

Signs of local neo-Nazi recruiting efforts spark concern

Conrad Sweatman 7 minute read Saturday, Sep. 26, 2026

A far-right canvassing push in Manitoba this month is raising concerns among Winnipeg residents.

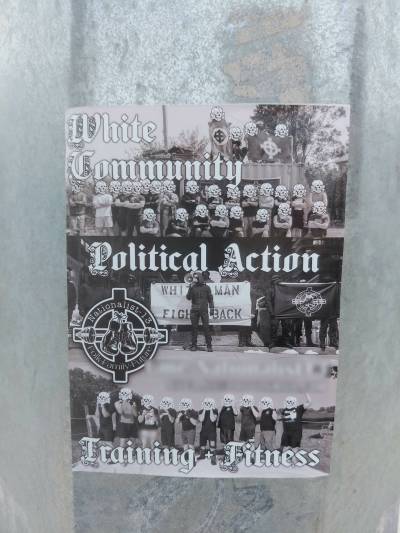
Stickers promoting Nationalist-13, a men’s-only neo-Nazi group also known as NS-13 based primarily in Hamilton, Ont., have appeared in Winnipeg and parts of southern Manitoba. The stickers bear national socialist branding and messages such as “White Man, Fight Back” and “White Community, Political Action, Training and Fitness.”

Winnipeg writer Jess Woolford recently encountered an NS-13 poster on Pembina Highway.

“It was appalling,” Woolford said. “It has the Nazi death heads covering people’s faces. It was pretty disturbing to come across this … I just didn’t expect to see it so blatantly displayed in my neighbourhood.”

Read
Saturday, Sep. 26, 2026