

Small business owners feel the credit crunch
Advertisement
Read this article for free:
or
Already have an account? Log in here »
To continue reading, please subscribe:
Digital Subscription
One year of digital access for only $205*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*First annual payment billed as $205.00 + GST for one year. This annual subscription will automatically renew at $233.00 + GST every 52 weeks (10% off the regular annual price of $259.35). Offer available to new and qualified returning subscribers only. Cancel any time.
To continue reading, please subscribe:
Add Free Press access to your Brandon Sun subscription for only an additional
$1 for the first 4 weeks*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*Your next Brandon Sun subscription payment will increase by $1.00 and you will be charged $17.95 plus GST for four weeks. After four weeks, your payment will increase to $24.95 plus GST every four weeks.
Read unlimited articles for free today:
or
Already have an account? Log in here »
Hey there, time traveller!
This article was published 11/04/2023 (1256 days ago), so information in it may no longer be current.
NEW YORK (AP) — When Nat West, owner of cider-making company Reverend Nat’s Hard Cider, decided to supplement his wholesale business by opening a taproom in a bustling neighborhood in Portland, Oregon, he thought getting financing would be a breeze.
After all, he was only seeking $50,000, has been in business for 11 years, and takes in more than $1 million in annual revenue.
In February and March, West reached out to three lenders he had previously gotten financing from, including one where he has an existing line of credit. To his surprise, he was rejected.
“I feel like it’s really weird, it’s such a small amount of money for a business that has so much ongoing, sustained revenue and has been in the same community for a long time,” he said.
West isn’t alone. Borrowing for small businesses was already constrained due to rising interest rates. Following the recent collapse of Silicon Valley Bank and Signature Bank, some lenders – particularly the small and midsize banks that serve small businesses — may be forced to tighten credit further, since they’re seeing an outflow of deposits, which means they need to retain capital. And banks are being more cautious in general due to uncertainty about the economy.
“It’s hard to read how severe this is going to be, but it’s certainly going to be significant and when you look at how things play out, small businesses are hit the hardest,” said Ray Keating, chief economist for the Small Business & Entrepreneurship Council.
According to the latest Biz2Credit Small Business Lending Index released in February, the approval rates of small business loan requests at big banks have fallen for nine consecutive months. The larger banks approved just 14.2% of applications in February, down from 28.3% in February 2020. Small banks granted about 20% of loan applications this February, but they were approving about half of all requests back in early 2020, before the pandemic hit.
An overall tightening of credit will help slow down the economy and ease inflation, which is what the Federal Reserve hopes to achieve by hiking interest rates, said Rohit Arora, CEO and co-founder of Biz2Credit. But that means that small businesses — a big job creator and source of innovation for the economy — will be left in the lurch.
“It will be the small companies that suffer the most if this continues,” he said.
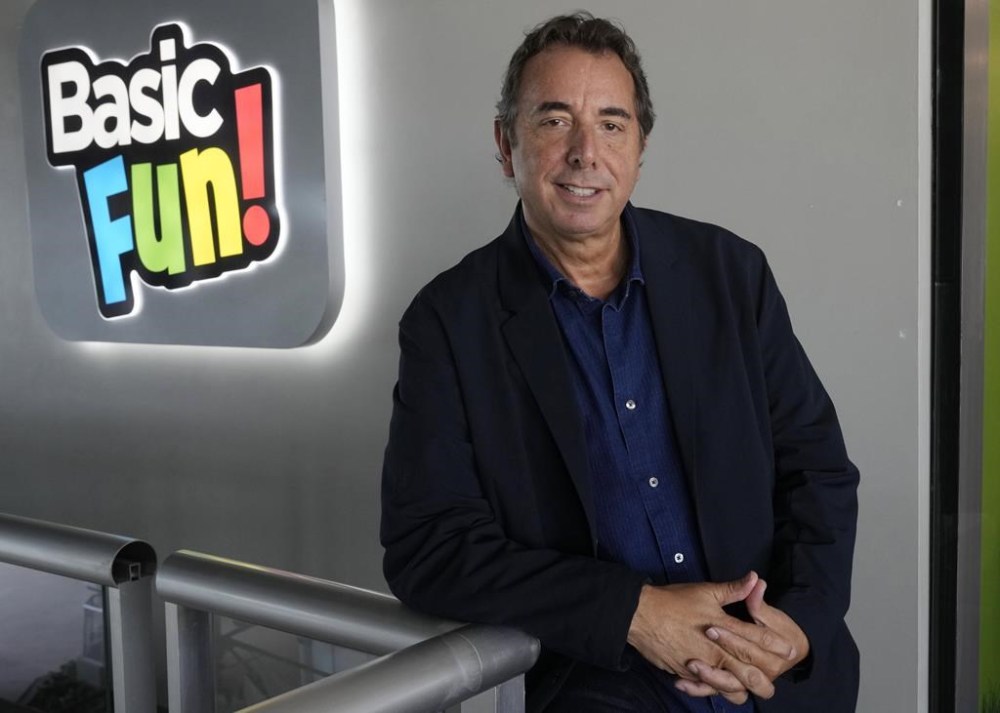
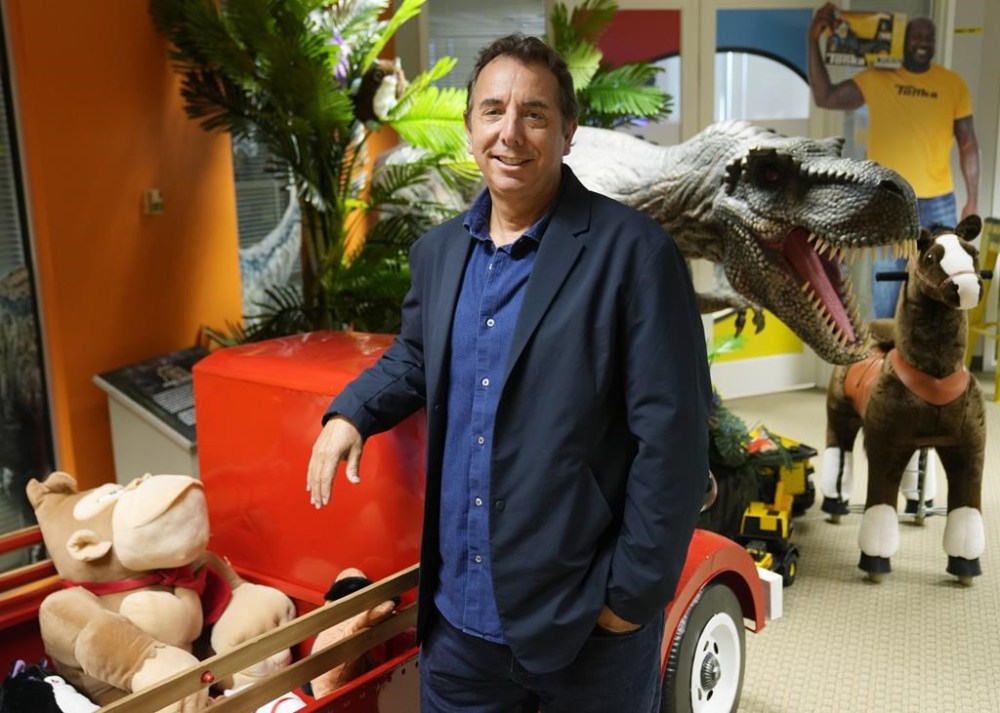
Basic Fun, a Boca Raton, Florida-based maker of such toys as Care Bears and Lincoln Logs, had to temporarily scuttle plans for an acquisition due to the crunch. CEO Jay Foreman said he was ready to go with non-binding agreements with 12 of the prospective 23 lenders lined up in late February and early March. But that number shrank to two after Silicon Valley Bank failed and triggered the recent banking turmoil.
“It’s just not the right timing now as lenders appear unclear about the broader credit markets and seem to be clutching the purse strings tightly at this point,” Foreman said. “We just have to ride this out until conditions are right to arrange the proper financing for our acquisition.”
Companies that have existing lines of credit are seeing interest rates increase. James Carron, who operates Flatirons Pharmaceuticals, in Longmont, Colorado, has seen rates increase for his line of credit that’s about $150,000. Before the pandemic, the rate was 6.99%, but that went up to 10%. Now it’s 13% and rapidly approaching 14%. Other potential lenders he contacted had even higher rates.
So, Carron said he’s put off the purchase of two servers and additional hardware security upgrades that he had planned for the first half of this year. He’s monitoring the economy now to see when he might be able to make the purchases.
A credit crunch affects small businesses more than larger ones, he said, because smaller businesses have fewer levers they can pull to get financing.
“We can’t issue corporate bonds or have other money available to us,” he said. “Large corporations have multiple avenues for them to secure reasonable rates for funding. A small business owner doesn’t have that ability.”

In the U.K., Dawn Barber has delayed some expansion plans because credit terms have gotten stricter. Barber is the founder and managing director at Web Shop Direct, which runs the online fashion brands UK Tights and UK Swimwear. She noted that her business has done well all through the pandemic, as her customers are looking to splurge on little luxuries.
Barber said that her business — which generates annual revenue of 2.5 million pounds ($3.1 million) — is essentially self-funded but when she recently turned to PayPal for extra funding, the financial terms were stricter compared to a year ago. Barber wanted to borrow 150,000 pounds ($186,195) but learned that she would get charged 10,000 pounds ($12,416) upfront, instead of the usual 6,000 pounds ($7,449) and that she needed to pay within six months, instead of nine months.
She decided the terms were too steep. She’s put a hold on officially launching a new line of wellness products, which includes loungewear and candles and was expected to account for 20% of her annual sales.
As for West, the Oregon cider-maker, he had to put $10,000 on his personal credit card to finance the new taproom, which is open. He’s still short of what he needs, but that will keep the taproom running for now, he said.
“I’m super thankful I can put it together,” he said. “A lot of people will just have to put their dreams on hold.”