

A bummer-summer forecast
Inflation subsiding as interest rates take bite out of wallets while financial prognosticators call for stormier weather ahead
Advertisement
Read this article for free:
or
Already have an account? Log in here »
To continue reading, please subscribe:
Digital Subscription
One year of digital access for only $205*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*First annual payment billed as $205.00 + GST for one year. This annual subscription will automatically renew at $233.00 + GST every 52 weeks (10% off the regular annual price of $259.35). Offer available to new and qualified returning subscribers only. Cancel any time.
To continue reading, please subscribe:
Add Free Press access to your Brandon Sun subscription for only an additional
$1 for the first 4 weeks*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*Your next Brandon Sun subscription payment will increase by $1.00 and you will be charged $17.95 plus GST for four weeks. After four weeks, your payment will increase to $24.95 plus GST every four weeks.
Read unlimited articles for free today:
or
Already have an account? Log in here »
Hey there, time traveller!
This article was published 22/07/2023 (1152 days ago), so information in it may no longer be current.
Nothing ruins a summer vacay like bad weather.
So, you may want to grab an umbrella because there’s a summer bummer economic and market outlook that will dampen your holiday plans.
A recent forecast from Deloitte Canada is predicting inflation will cool even more than it already has.
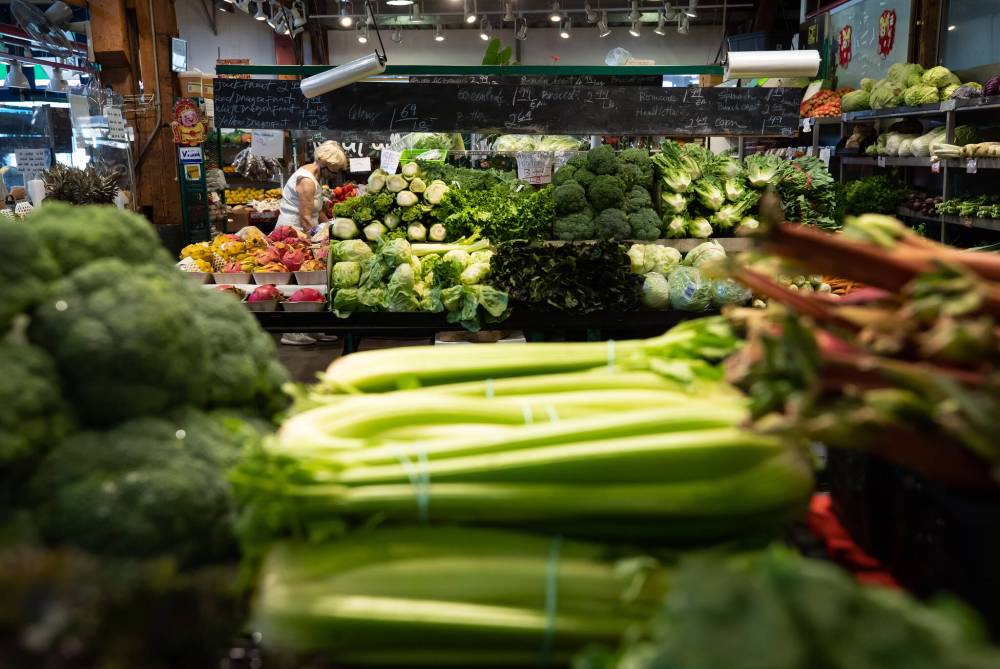
DARRYL DYCK / THE CANADIAN PRESS FILES
Inflation is down from a high of eight per cent last summer but remains high for groceries and housing. A recent forecast from Deloitte Canada is predicting that inflation will cool even more than it already has.
That’s a good thing, right?
It is indeed.
Yet this quest of central banks to hike rates to cool high inflation —which if left unchecked deeply harms consumers and can trigger a deep recession — to lead the economy to a “soft landing” (slower growth but not a recession) that can still inflict pain upon consumers.
“The cost to finance their debt —principally their mortgages — means they will have less money to spend,” says Deloitte Canada’s chief economist Dawn Desjardins in a recent interview with the Free Press.
As well, inflation — while down from a high of eight per cent last summer — remains high for groceries and housing.
Recent data from TransUnion offers insight.
The credit bureau polled consumers and found about a third of respondents feel as though we’re already in a recession even though we’re not, while about one in four believe a recession is coming before the end of the year.
“Over time, (conditions) could make it more challenging to make loan, credit card, lease or mortgage repayments, which could potentially lead to an increase in delinquency,” says Matt Fabian, director of financial services research and consulting at TransUnion.
One upside to the current environment is individuals who want to work likely can.
The labour market remains hot with historically low unemployment.
In fact, the abundance of job openings is now a key driver of inflation because employers must pay higher wages to attract workers. For central bankers, this is now a main fuel for inflation — more so than previous factors such as post-pandemic revenge spending, the war in Ukraine and supply chain difficulties, Desjardins says.
Even though unemployment rose slightly to 5.4 per cent in June, “we are likely to see rates remain higher for quite a long time as central banks are signaling” the need to cool job and wage growth, she adds.
Housing costs also remain problematic.
Sure, prices have eased with higher rates, but Canada continues to see record immigration, which is needed to fill the job openings and help execute the soft landing for the economy.
“We have a lot of people coming to Canada and not enough housing.” That drives up housing prices, particularly rent, Desjardins says.
Although everyone hopes the economy sticks a soft landing, some observers — including the world’s largest asset manager Blackrock — see a rising risk of a recession.
Count among them Toronto portfolio manager John De Goey, author of Bullshift — How Optimism Bias Threatens Your Finances.
“We have a severely inverted yield curve, and it’s becoming more so with each interest rate hike,” says the investment adviser with Designed Wealth Management.
An inverted curve means short-term interest rates are higher than long-term interest rates. That’s the opposite of normal. Typically, the longer the loan term, the higher the interest rate.
Every so often, the curve inverts and more often than not, a recession follows.
But a recession hasn’t happened yet even though we have had an inverted yield curve since early in the second half of last year, De Goey says, adding inverted curves normally last only a few weeks.
What’s more, in most instances, the curve is inverted by only about 15 basis points (0.15 per cent).
So, a two-year bond yield would be about 0.15 percentage points higher than a 10-year bond yield when the curve inverts. But this time, the inversion is much steeper. Two-year yields are about 100 basis points — one full percentage point — higher than 10-year yields rates, De Goey says.
This is partly due to the velocity — less than 18 months — by which central banks have increased rates 475 basis points.
At the same time, many investors are allocating more capital to long-term bonds because they fear higher interest rates will lead to a recession, which would inevitably involve a bear market with stock prices falling 20 per cent or more.
Higher demand for long-term bonds increases their price on the bond market, which drives down their yields (return). But investors are willing to pay more for less yield because they anticipate that when a recession comes, central banks will lower interest rates to stimulate economic growth. In turn, long-term bondholders will benefit most because falling interest rates increase the value of the bonds they hold.
Many then sell some of those bonds at a profit, then invest the returns in the stock market when stock prices are low.
That scenario — a recession, a bear market and falling interest rates — is unlikely to play out in the next few months. Instead, interest rates are more likely to move slightly higher, De Goey predicts.
Central bankers “are signalling they will keep hiking rates until it hurts” enough to cool economic growth and drive inflation back to the ideal target of two per cent, he says.
In the meantime, tilting investment portfolios toward conservative investments, such as bonds and GICs, is probably prudent, De Goey says.
“Be as conservative as you can be while still respecting your overall risk profile.”

For a balanced portfolio, that could mean shifting from 60 per cent stocks and 40 per cent bonds to 50 per cent stocks and 50 per cent bonds, he adds.
For the stock side of the portfolio, De Goey suggests moving increasingly away from growth stocks such as technology, which have done well for many years, to more defensive stocks such as consumer staples that remain in demand during a recession.
Of course, nothing is guaranteed, he adds.
“But we’re in for a rough ride until the end of 2024 in all likelihood,” De Goey says, noting by then a recession and bear market should have run their course.
“With the caveat that psychics exist to make economic and market forecasters look good.”
Related Articles
Budgeting on fun as living costs rise
Advertisement Advertise With Us
Advertisement Advertise With Us