

Shining light of knowledge on money fears
Canadians have plenty of financial anxieties, surveys show; best cure is literacy
Advertisement
Read this article for free:
or
Already have an account? Log in here »
To continue reading, please subscribe:

Digital Subscription
One year of digital access for only $205*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*First annual payment billed as $205.00 + GST for one year. This annual subscription will automatically renew at $233.00 + GST every 52 weeks (10% off the regular annual price of $259.35). Offer available to new and qualified returning subscribers only. Cancel any time.
To continue reading, please subscribe:
Add Free Press access to your Brandon Sun subscription for only an additional
$1 for the first 4 weeks*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*Your next Brandon Sun subscription payment will increase by $1.00 and you will be charged $17.95 plus GST for four weeks. After four weeks, your payment will increase to $24.95 plus GST every four weeks.
Read unlimited articles for free today:
or
Already have an account? Log in here »
Hey there, time traveller!
This article was published 02/11/2024 (697 days ago), so information in it may no longer be current.
Fear of the unknown underpins all kinds of anxieties. That’s certainly so for money-fuelled worries.
Two recent surveys, released ahead of Financial Literacy Month in November, suggest as much.
One that was conducted on behalf of the Canada Pension Plan (CPP) Investments, released Oct. 30, found 61 per cent of Canadians fear running out of money in retirement.
Supplied
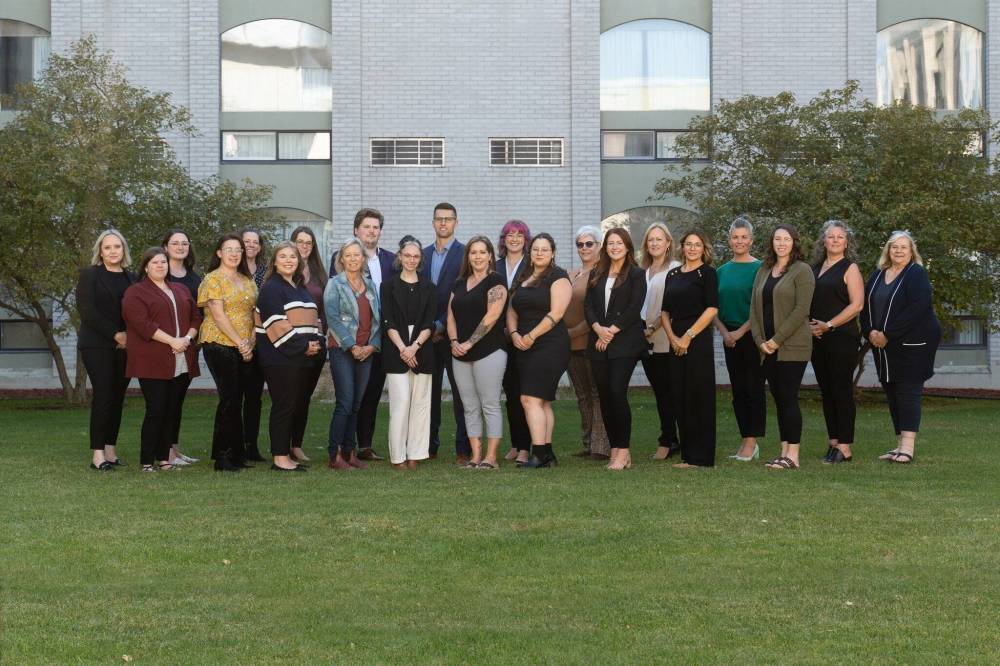
Access Credit Union team of financial literacy educators
It also uncovered that among young Canadians — ages 18 to 25 — 63 per cent feel “a lot of anxiety about making the wrong decisions” about money. That fell to 33 per cent for respondents 65 and older, suggesting perhaps there’s something to the notion that wisdom comes with age.
It may also point to knowledge — especially in finance — can be fear’s antidote.
The second survey, done for wealth management firm Edward Jones, further supports this premise, finding 84 per cent of those surveyed believe financial education in school would have helped them with money management in adulthood, reducing their stress.
These reports probably aren’t all that surprising to folks struggling with rising costs, saving and investing for the future or trying to get out from under increasingly weighty debt.
Yet, the best weapon against their problem is one that is increasingly on tap from non-profit organizations and financial institutions across Canada.
That’s knowledge or more aptly: financial literacy
Many organizations are this month pushing the message that knowledge is indeed power.
“What we’re hearing and learning from these studies and our clients is that money knowledge is critical to financial well-being,” says Maryon Urquhart, director for community impact programs at Edward Jones Canada.
Often, many Canadians — facing the daunting challenges of getting by economically, let alone saving for the future — turn to experts.
To that end, the Edward Jones study found 75 per cent of Manitobans seek to work with a financial adviser or already have one.
“Working with an adviser can give people a baseline of money concepts,” she says. “Financial advisers help you with that discovery process of what your goals are.”
It’s less about discussing investments and more about life goals, dreams, needs and wants. From there, advisers build a plan with the right investments to underpin it.
Then again, not everyone knows where to turn. That’s why a local credit union is bringing financial literacy to the community.
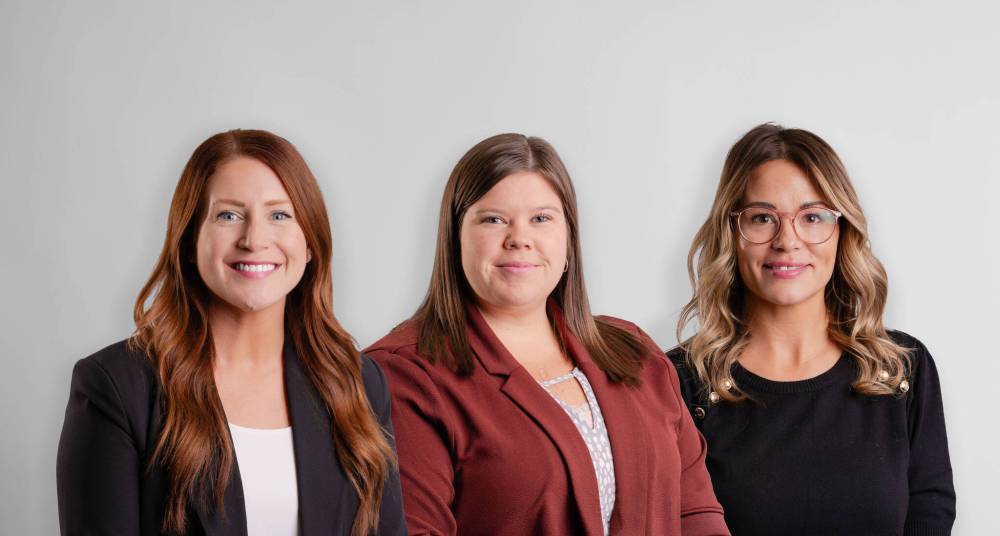
Access Credit Union has three designated financial literacy coaches: Keesy Rodewald, Janessa Unrau and Emily Suderman.
Their job involves not just working with the community; it’s focused on training other credit union employees to bring financial literacy to Manitobans.
Central to that is familiarizing credit union representatives with 17 different workshops, developed by a consortium of Canadian credit unions under the banner of “Each One. Teach One.” (EOTO).
“These are created in plain language that’s easy to understand so that when we’re going into community groups, schools and places of business, participants can quickly grasp these concepts and apply them to their own lives,” says Rodewald, also a community engagement specialist at Access.
Among the covered are basic banking, loans, investing, home ownership and budgeting.
“You don’t have to be an Access member — these are for everyone” says Suderman, also a learning and development specialist at Access.
Started in 2017, Access’s financial literacy initiative has run more than 250 free workshops, many in high schools, including 30 this year, with many more scheduled for November.
Supplied
Access Credit Union designated financial literacy coaches (left to right): Emily Suderman, Learning and Development Specialist, Janessa Unrau, Manager Recruitment, and Keesy Rodewald, Community & Engagement Specialist
“Financial literacy is one of Access’s main pillars and so this is definitely one way we promote that strong focus,” says Unrau, also manager of recruitment at Access.
After all, a financially literate population typically leads to a more financially healthy population, which is ultimately beneficial for financial co-operatives like Access, given Manitobans make up its membership.
And the better off each member is financially, the better off the collective — the credit union — is, she notes.
Similarly, the more Canadians understand about foundational aspects of finance — like CPP — the better for society as a whole.
“People who understand the role that CPP plays in their retirement income are also less stressed,” says Frank Switzer, managing director of public affairs and communications with the Canada Pension Plan Investments.
Consider that fear of running out of money in retirement. In Canada, that doesn’t really happen, especially if you worked and contributed to CPP. You’re guaranteed income. Beyond that, you will have Old Age Security (OAS) and, if necessary, the Guaranteed Income Supplement (GIS).
Another notable point about CPP is it’s rock solid. Most worker contributions today do go out to pay current pensions, Switzer notes.
Yet, a small portion goes to the CPP Investment Fund — today worth more than $600 billion — to help provide future pension payments when contributions from workers may not be enough to meet payments for retirees.
That scenario is expected to happen sometime in the 2030s, Switzer adds, but the latest actuary report on its solvency forecasts the CPP fund will be able to keep the pension plan solvent for at least 75 years.
So those worried young adults in the CPP survey can take some measure of assurance, Switzer says.
“Knowing you have a head-start (saving for retirement) through CPP can make retirement feel a lot more achievable.”

That said, CPP and OAS are likely not going to get the job done for most Canadians’ vision of retirement.
“Their lifestyle may need to be curtailed,” says Urquhart, adding if Canadians rely on CPP alone and do not have a workplace pension plan or additional savings like an RRSP.
That’s where knowledge — which often will be provided by a trusted licensed adviser — can help build a plan to budget, save and invest.
Joel Schlesinger is a Winnipeg-based freelance journalist
joelschles@gmail.com