

Dollarama sees Iran war driving up freight costs, but unlikely to weigh on forecast
Advertisement
Read this article for free:
or
Already have an account? Log in here »
To continue reading, please subscribe:
Digital Subscription
One year of digital access for only $205*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*First annual payment billed as $205.00 + GST for one year. This annual subscription will automatically renew at $233.00 + GST every 52 weeks (10% off the regular annual price of $259.35). Offer available to new and qualified returning subscribers only. Cancel any time.
To continue reading, please subscribe:
Add Free Press access to your Brandon Sun subscription for only an additional
$1 for the first 4 weeks*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*Your next Brandon Sun subscription payment will increase by $1.00 and you will be charged $17.95 plus GST for four weeks. After four weeks, your payment will increase to $24.95 plus GST every four weeks.
Read unlimited articles for free today:
or
Already have an account? Log in here »
Dollarama says the prolonged war in Iran is expected to drive up freight costs for the rest of the year, but it’s unlikely to weigh on its current outlook.
“The slight nuance this quarter is that we’re saying that we can maintain this guide despite assuming that there will be elevated oil prices for the remainder of the year,” chief financial officer Patrick Bui told analysts on the company’s second-quarter earnings call on Wednesday.
“That is a little bit different than last quarter, where we said our guide remains as long as prices normalize.”
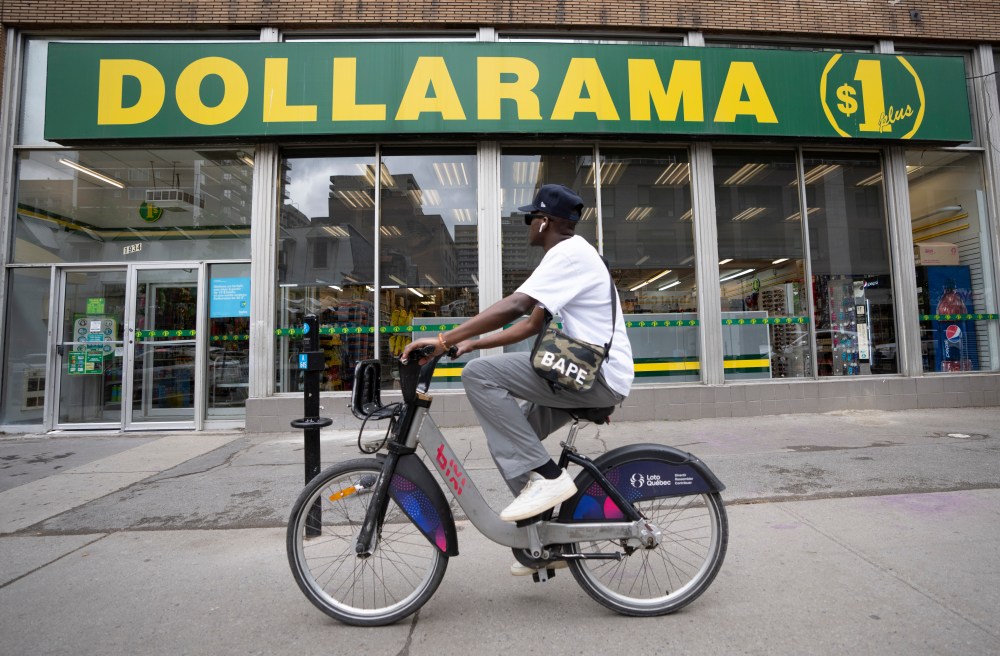
Bui’s remarks came as many retailers are already feeling the effects of the Middle East conflict. Fuel costs have sharply risen because the war has choked the Strait of Hormuz, a critical seaway for one-fifth of the world’s energy supply. Importers and exporters have also seen shipping expenses rise as they reroute goods away from the Middle East.
Bui said that if the situation remains the way it has been in recent days, he remains “comfortable” with the current forecast on gross profit for the full year.
Oil prices on Wednesday were trading north of US$100 per barrel as fighting in the region has escalated over the past week.
Dollarama chief executive officer Neil Rossy dismissed any speculation about price increases from the current cap of $5, which it positions as its core business strategy.
But that could change if costs climb significantly.
“The key trigger would be cost inflation reaching a level where we can no longer sustainably support the current $5 max price point,” he said.
“However, based on what we’re seeing today, we don’t believe that an additional price point is necessary.”
Dollarama executives had previously indicated that the war would drive up costs for gathering raw materials, producing inventory and moving it from factories to distribution warehouses and then on to stores.
However, the company still maintained most of its guidance and raised its forecast for Canadian comparable store sales for the 2027 financial year to between four and 4.5 per cent, up from three to four per cent earlier.
It also expects net new store openings to total between 65 and 75 in Canada, up from earlier expectations for 60 to 70.
“When it comes to guidance, I would say on the one hand, our strong performance in the first-half supports the positive revision to the full-year outlook,” Bui said.
“On the other hand, I think it’s important to remain prudent for the balance of the year, given the ongoing uncertainties in the macro-environment we all know about — whether that’s higher oil prices or trade headlines.”
The discount retailer reported a second-quarter profit of $349.3 million, up from $321.5 million in the same quarter last year. Its profit amounted to $1.29 per diluted share for the quarter ended Aug. 2, up from $1.16 per diluted share a year earlier.
Sales for the quarter amounted to $2.03 billion, up from $1.72 billion.
Comparable store sales in Canada rose 5.4 per cent in the quarter, including a 3.7 per cent increase in the number of transactions and a 1.7 per cent increase in average transaction size.
RBC analyst Irene Nattel said Dollarama’s core operations in Canada and Latin America delivered better-than-expected results.
She said in a note the second-quarter results put the company on good footing to achieve its updated 2027 outlook for Canada.

Dollarama shares touched a 52-week low on Tuesday, but closed 5.47 per cent higher at $174.56 on Wednesday.
“We believe that these results will reassure investors, as despite current economic headwinds in Canada, Dollarama should continue to gain market share and grow earnings at a healthy pace,” Martin Landry, managing director in equity research at Stifel Canada, said in a note on Wednesday.
This report by The Canadian Press was first published Sept. 16, 2026.
Companies in this story: (TSX: DOL)
Note to readers:This is a corrected story. A previous version incorrectly stated the Q2 profit figure at $359.3M in the headlines. In fact, it’s $349.3M.