

‘There is so much to learn’
Dementia often involves profound financial challenges for individuals and their families made all the more difficult by an early diagnosis years before retirement
Advertisement
Read this article for free:
or
Already have an account? Log in here »
To continue reading, please subscribe:
Digital Subscription
One year of digital access for only $205*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*First annual payment billed as $205.00 + GST for one year. This annual subscription will automatically renew at $233.00 + GST every 52 weeks (10% off the regular annual price of $259.35). Offer available to new and qualified returning subscribers only. Cancel any time.
To continue reading, please subscribe:
Add Free Press access to your Brandon Sun subscription for only an additional
$1 for the first 4 weeks*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*Your next Brandon Sun subscription payment will increase by $1.00 and you will be charged $17.95 plus GST for four weeks. After four weeks, your payment will increase to $24.95 plus GST every four weeks.
Read unlimited articles for free today:
or
Already have an account? Log in here »
Hey there, time traveller!
This article was published 04/06/2022 (1575 days ago), so information in it may no longer be current.
The start of Nancy and Randy Scott’s journey with Alzheimer’s disease began itself on a literal journey.
“We were on holidays in Vancouver in 2018, Randy’s hometown, and while I was driving he kept giving me directions where he would say to turn right but pointed left,” says Nancy, 57, a registered nurse and department head for the health-care aide training program at Herzing College in Winnipeg.
“Most people will mix that up once, but he did it four times in a row.”
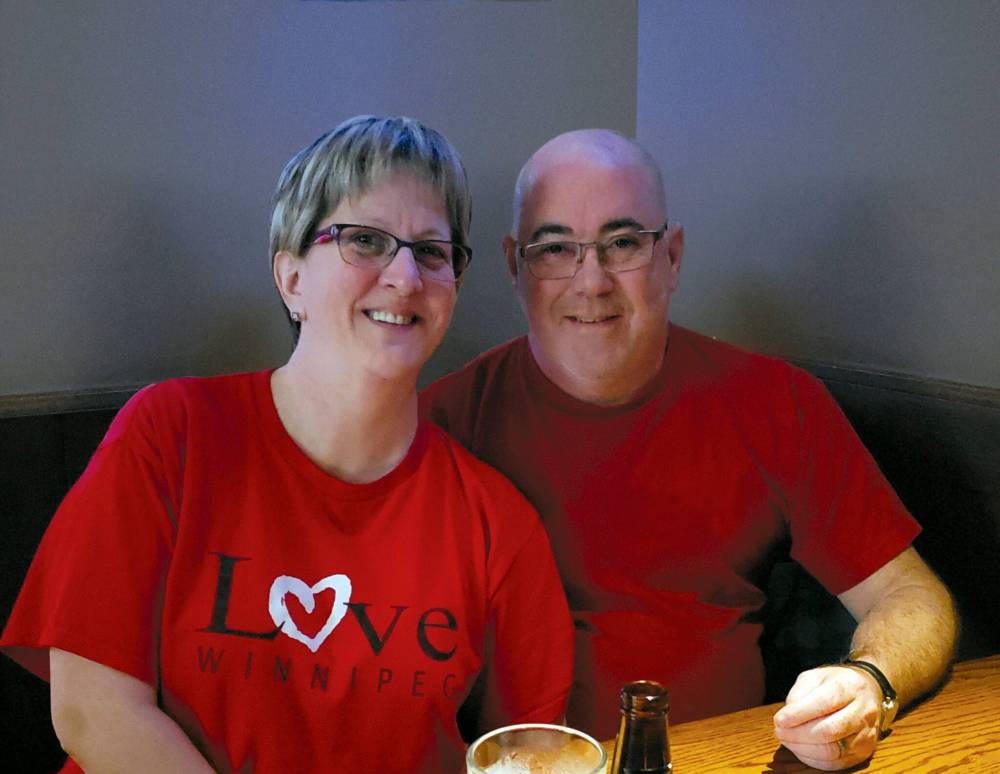
As Nancy further explains, a typical diagnosis often comes a few years after Alzheimer’s disease emerges.
“We were fortunate in a sense because he exhibited a clear sign of dementia right there: language impairment.”
The journey from those early symptoms to diagnosis to managing the day-to-day of Alzheimer’s has had many challenges, including finding ongoing care so Randy, 56, could remain at home while Nancy continues working.
Among the most difficult has been dealing with upheaval to financial lives, Nancy says.
“We’re really still in the middle of our lives.”
Randy is one of an estimated 28,000 individuals in Canada diagnosed with the neurological disorder before age 65.
Not only does Alzheimer’s slowly erode their health, independence and sense of who they once were, it often throws retirement plans into disarray.
The potential financial challenges are not lost on the sponsors of the Alzheimer Society of Canada’s largest fundraising event, the IG Wealth Management Walk for Alzheimer’s taking place today at St. Vital Park.
“It’s a huge issue in Canada,” says Aurele Courcelles, assistant vice-president of tax and estate planning at IG Private Wealth Management.
“More than 700,000 Canadians are living with dementia, and the numbers are forecast to reach about one million by 2032.”
Not only are individuals with the disease affected; it’s often their spouse and other family members too.
Courcelles says early onset is especially difficult when individuals have no financial plan in place to deal with “worst case scenarios” like early onset Alzheimer’s.
“When you’re healthy, you tend to think these things are never going to happen,” he adds.
At a minimum, individuals should include in their basic financial plan a will, power of attorney and living will.
A power of attorney and living will — also called a health-care directive — are most critical to have before individuals develop Alzheimer’s.
And for those without, Courcelles recommends getting them in place as soon as possible while individuals are still capable of choosing someone they trust to manage their money and health-care decisions when they can no longer make those choices on their own.
If they do not, families risk a longer, more complicated process that can involve the courts, he adds.
Other key considerations include taking a closer look at workplace disability insurance, assessing whether additional cover may be warranted or, in the case of self-employed individuals, determining how much private coverage they can afford.
Another helpful planning strategy is simply building up an emergency savings account.
“People think of a rainy-day fund for if they lose their job or need to repair the roof,” Courcelles says.
This savings pool will not solve all financial problems resulting from early onset dementia, but “at least the money might carry people through that first tough period,” he adds.
Indeed there is much to figure out early on, says Erin Crawford, program director at the Alzheimer Society of Manitoba.
“It’s not just about the cost; you need a different kind of financial plan in place to maximize quality of life now and down the road,” she says.
In the case of Nancy and Randy, their retirement plan was still taking shape when he was diagnosed. They envisioned retiring around age 65, and they still had a mortgage, car loan, credit card bills and line of credit debt to pay off before then.
“There is so much to learn so quickly,” Nancy says.
Randy, a carpenter, did have disability insurance through an employer that, when combined with Canada Pension Plan Disability, amounts to about $2,000 a month before taxes.
They also remortgaged to eliminate credit card debt and add a little extra room for additional expenses.
Most people with early diagnosis of dementia aim to stay in their home as long as possible, and while “there is home care funded through Shared Health from the province, but it is limited and often not sufficient for people’s needs,” Crawford says.
Additionally many people with dementia eventually move to a personal care home because they can longer live safely in their home.
Long-term care costs are based on income, but because couples are often separated, their household costs effectively double, Crawford says.
Home care was not a good fit for Randy and Nancy because Randy required supervision while Nancy worked full-time.

Instead they chose a more robust but complex option offered by the Winnipeg Regional Health Authority called the Self and Family Managed Care program and paid for by the province.
“It’s quite the process; there is so much to learn,” Nancy explains. “You kind of have to become a business, registering with Canada Revenue Agency,” and it can involve hiring and training individuals, and even managing payroll.
Today the couple is in a manageable, though still challenging, place.
With many of the care and financial issues addressed, Randy and Nancy can now focus on making the most of the time they have together, which includes travelling as much as possible to visit family and friends, Nancy says.
“I felt it was really important that he gets to do what he wants to do, so I asked him, ‘What’s on your bucket list?’”