Investor strange love
Advertisement
Read this article for free:
or
Already have an account? Log in here »
To continue reading, please subscribe:
Digital Subscription
One year of digital access for only $205*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*First annual payment billed as $205.00 + GST for one year. This annual subscription will automatically renew at $233.00 + GST every 52 weeks (10% off the regular annual price of $259.35). Offer available to new and qualified returning subscribers only. Cancel any time.
To continue reading, please subscribe:
Add Free Press access to your Brandon Sun subscription for only an additional
$1 for the first 4 weeks*
- Enjoy unlimited reading on winnipegfreepress.com
- Read the E-Edition, our digital replica newspaper
- Access News Break, our award-winning app
- Play interactive puzzles
*Your next Brandon Sun subscription payment will increase by $1.00 and you will be charged $17.95 plus GST for four weeks. After four weeks, your payment will increase to $24.95 plus GST every four weeks.
Read unlimited articles for free today:
or
Already have an account? Log in here »
Risk and reward seem like polar opposites. Yet when it comes to investing, greater risk yields greater potential reward.
The other side of that coin, however, is the greater the reward you seek, the greater the risk of losing money. This is a fundamental principle (and a paradox) of investing.
A new book by a popular investment blogger and veteran institutional money manager tackles this often fraught yet very fruitful relationship.
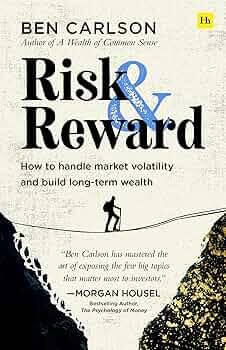
Risk & Reward: How to Handle Market Volatility and Build Long-term Wealth, published earlier this month, builds on Ben Carlson’s popular behavioural investing-focused blog, “A Wealth of Common Sense.”
Based in Grand Rapids, Mich., Carlson wants to inoculate average investors against their own knee-jerk reactions to market crashes, while adhering to essential tenets of successful long-term investing.
“There’s more acceptance of risk than there’s ever been,” says Carlson, an investment analyst and director of institutional asset management at New York City-based Ritholtz Wealth Management.
That’s partly a result of the 2008-09 Financial Crisis. In its wake, even institutional clients were “investing from the fetal position,” fearing the next crash.
As markets recovered and then grew into the extended bull market we’re still in today, the collective investor mindset regarding market crashes has shifted. Many investors see deep stock market declines as an opportunity.
And that’s not a bad thing, Carlson says. “Enough people have realized that when items go on sale, you don’t run from the store.”
That’s led to quick recoveries from the COVID-19 pandemic crash, the post-pandemic rising rate environment, and why investors have powered through the war in Iran and other upheaval driven by United States trade policies.
It’s a strange kind of love whereby more investors’ capitalist hearts are stirred by falling asset prices.
There’s simply more acceptance of risk today; an understanding that when stock prices fall dramatically and collectively, it is often a good time to buy great companies at a discount.
Or savvy investors can simply buy the entire market — like the S&P TSX Composite Index — at a bargain price via low-cost, exchange-traded funds (ETFs).
Carlson, by the way, is a proponent of passive ETFs for average investors to get market exposure. He also suggests most people stick to basic portfolio construction like 60 per cent stocks and 40 per cent bonds — known as the “60-40.”
“A plain vanilla portfolio is fine for the majority of investors, as long as they can stick with it.”
The ability to be steadfast is critical, he notes, and speaks to the need to manage risk so we don’t do something unprofitable, though understandable: panic-selling investments when prices are falling.
Diversification helps prevent that negative outcome, and a 60-40 strategy — or some permutation, like a more aggressive approach of 80 per cent stocks and 20 per cent bonds — is the most straightforward approach to diversification.
The reason is most days stocks and bonds are inversely correlated. When stocks collectively fall, bond values collectively rise. This dampens the volatility of the overall portfolio.
As long as investors can limit selling investments at a loss, understanding prices generally recover, they will come out the other side of periods of market upheaval wealthier.
One challenge is when markets are at all-time highs — like today — driven by themes like the use case for artificial intelligence. Diversification can feel a little dull.
“Diversification is like giving up on trying to hit home runs, to avoid striking out and trying to hit a lot of singles and doubles.”
Carlson adds diversification often feels slightly off-putting, especially during bull markets because it inevitably involves owning investments “you do not like” because they are down in value.
“That trade-off piece is the hardest one,” he says. But sticking to the plan can help avoid buying high and selling low — destroyers of wealth.
He uses past market crashes to explain how diversification helps investors manage markets’ ups (greed) and downs (fear). More broadly, adhering to diversification, portfolio rebalancing and dollar-cost-averaging helps turn risk into long-term reward.
For instance, rebalancing (i.e. once a year) to ensure your desired asset mix — like 60-40 — is reflected, enforces built-in discipline of selling high and buying low.
Similarly, dollar-cost-averaging involves allocating buying more assets when prices are down — because that set monthly amount simply has more purchasing power — and fewer assets when prices are high.
In discussing events like the 1929 stock market crash and Great Depression, which destroyed many investors’ capital, Carlson shows how these basic principles can help limit downside risks while increasing reward over time.
“In the case of the 1929 crash, the U.S. market did not achieve a new high until 1954,” he says.
In that situation, dollar-cost-averaging would be beneficial. An investor gradually and consistently buying into the market would still see growth over that 25-year span.
It’s a notable reminder today.
“Risk is really the one constant in the market, even if it appears sometimes to go into hibernation,” he says.
Indeed, risk seems sleepy lately despite many worries.

That doesn’t mean investors should dive into markets or shun them. Euphoria-driven markets can last longer than what seems reasonable.
Having a systematic, diversified strategy guided by long-term needs is the best way to allow risk to do heavy lifting.
Taking readers through periods of upheaval, like the stagflation of the 1970s, Carlson underscores that markets recover. Albeit some recoveries are long. “But the math tells you most of the time the stock market goes up.”
On average, the U.S. stock market has risen in value every three of four years, Carlson adds.
“So if you have the right mindset, a crash can be a good thing, especially if you can put money to work into it and lean into the pain.”