Liz Weston: Safer ways to raid your retirement, if you have to

Advertisement

Advertise with us

Raiding your retirement accounts can be expensive. Withdrawing money before age 59 1/2 typically triggers income taxes, a 10% federal penalty and — worst of all — the loss of future tax-deferred compounded returns. A 30-year-old who withdraws $1,000 from an individual retirement account or 401(k) could lose more than $11,000 in future retirement money, assuming 7% average annual returns.

Read this article for free:


or

Already have an account? Log in here »

To continue reading, please subscribe:

Subscribe and receive a limited-edition Free Press branded hat or tote.

Digital Subscription

One year of digital access for only $205*

  • Enjoy unlimited reading on winnipegfreepress.com
  • Read the E-Edition, our digital replica newspaper
  • Access News Break, our award-winning app
  • Play interactive puzzles

*First annual payment billed as $205.00 + GST for one year. This annual subscription will automatically renew at $233.00 + GST every 52 weeks (10% off the regular annual price of $259.35). Offer available to new and qualified returning subscribers only. Cancel any time.

To continue reading, please subscribe:

Add Free Press access to your Brandon Sun subscription for only an additional

$1 for the first 4 weeks*

  • Enjoy unlimited reading on winnipegfreepress.com
  • Read the E-Edition, our digital replica newspaper
  • Access News Break, our award-winning app
  • Play interactive puzzles
Start now

*Your next Brandon Sun subscription payment will increase by $1.00 and you will be charged $17.95 plus GST for four weeks. After four weeks, your payment will increase to $24.95 plus GST every four weeks.

Hey there, time traveller!
This article was published 26/06/2023 (1196 days ago), so information in it may no longer be current.

Raiding your retirement accounts can be expensive. Withdrawing money before age 59 1/2 typically triggers income taxes, a 10% federal penalty and — worst of all — the loss of future tax-deferred compounded returns. A 30-year-old who withdraws $1,000 from an individual retirement account or 401(k) could lose more than $11,000 in future retirement money, assuming 7% average annual returns.

In the past, there were a few ways you could avoid the penalty. Congress recently added several more, and some of those exceptions allow you to repay the money within three years. That would allow you to get a refund of the taxes you paid and — best of all — allow the money to start growing again, tax deferred, for your future.

You’re still better off leaving retirement funds alone for retirement, says Erin Itkoe, director of financial planning at Tarbox Family Office, a wealth management firm in Scottsdale, Arizona. If you can’t, though, you could at least limit the damage from taking the money out early, she says.
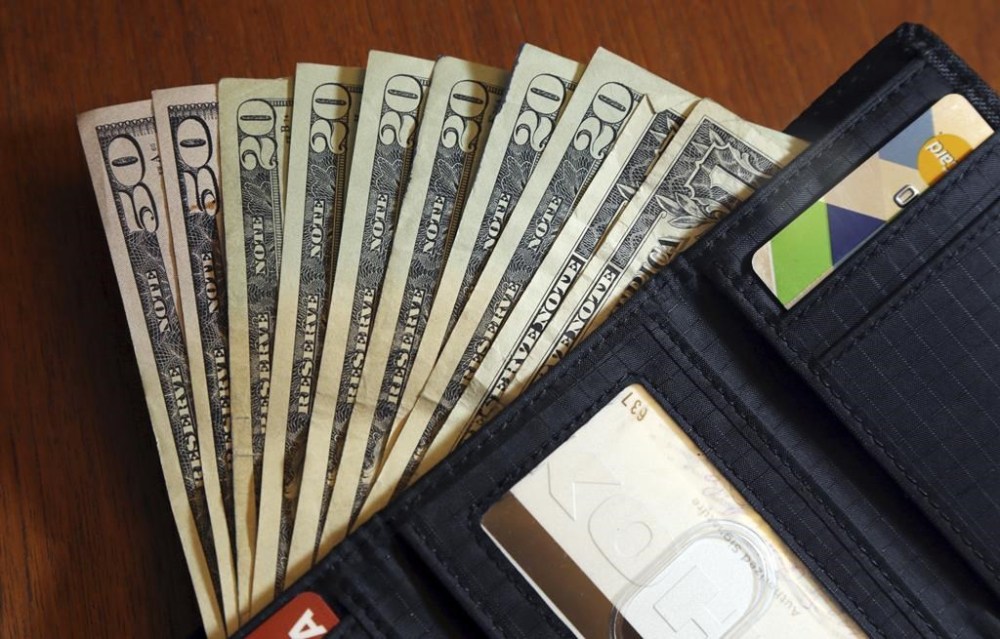
FILE - Cash is fanned out from a wallet in North Andover, Mass., June 15, 2018. Parenting comes with many responsibilities, and one is raising financially independent kids. Generally, it’s best to leave the money in your retirement accounts safely tucked away. Withdrawing money early can trigger taxes and a 10% penalty, plus it can cut into what you otherwise would’ve had for retirement. (AP Photo/Elise Amendola, File)

WHAT YOU NEED TO KNOW ABOUT SECURE 2.0

The new penalty exceptions are part of Secure 2.0, a package of retirement plan changes that Congress passed late last year. Some exceptions are available for your IRA right now, while others take effect in coming years, says David Certner, legislative counsel for AARP. The exceptions also can apply to workplace plans, such as 401(k)s or 403(b)s, but it may require your employer to opt in, so check with your human resources department, Certner says.

However, the repayment option still isn’t available for most penalty exceptions. For example, you can avoid the penalty if you withdraw $10,000 from an IRA for a first-time home purchase or to pay higher education expenses, but you won’t be able to repay the money later and get the taxes refunded.

DISASTERS, TERMINAL ILLNESS AND FAMILY EXPANSION

One new penalty exception that allows for repayment is for disasters. People who live in a federally declared disaster area and suffer an economic loss can withdraw up to $22,000 penalty-free. Income taxes still have to be paid on the withdrawal but the income can be spread over three years to reduce the potential tax impact. This exemption was made retroactive to Jan. 26, 2021.

Another potentially large exemption with the repayment option is one for terminal illness. Effective this year, the 10% penalty is waived for people whose doctor certifies that they are expected to die within seven years, says Itkoe, who’s also a certified public accountant serving on the American Institute of CPAs’ personal financial planning executive committee. There’s no limit on how much can be withdrawn.

A three-year repayment period also now applies to the penalty exception when you have or adopt a child. This exception allows each parent a $5,000 withdrawal within the 12 months after a child is born or adopted.

EXCEPTIONS FOR DOMESTIC ABUSE AND FINANCIAL EMERGENCIESTO COME

Next year, the 10% penalty is waived for victims of domestic abuse. The penalty-free withdrawal is limited to the lesser of $10,000 or 50% of the account’s value and can be repaid over three years.

Also effective next year is a penalty-free distribution of up to $1,000 for some emergency expenses. People can take one such withdrawal per year if the money is repaid. Otherwise, only one distribution is allowed every three years.

Note that both of these exceptions are “self-certified.” That means you provide a written statement asserting that you meet the requirements without having to supply other documents or proof, says Itkoe.

OTHER SECURE 2.0 PENALTY EXCEPTIONS

A penalty exception to pay for long-term care insurance kicks in for 2026, but it only applies to workplace plans, not IRAs. Note that the withdrawal — which is limited to the lesser of $2,500 or 10% of the account balance — can only be used to pay insurance premiums, not to pay for the actual care, Certner notes.

Secure 2.0 also expanded the “public safety employee” exception for early withdrawals from workplace plans.

In the past, the 10% penalty didn’t apply for withdrawals from workplace plans if the worker left a job in the year they turn 55 or older, or age 50 for public safety employees. Now, private sector firefighters and state and local corrections officers also can qualify for the public safety exception after they turn 50. In addition, public safety employees with at least 25 years of service with the employer sponsoring the plan can now avoid the penalty regardless of their age.

This is just a summary of the new penalty exceptions. The rules are complex enough that people should consult a tax professional before taking a withdrawal, Itkoe says. The pro also can help file an amended tax return if the withdrawal is repaid.

But no one should assume that the exceptions make retirement plan withdrawals a good idea, since most people won’t pay the money back even if they have the option to do so, she says.

“Drawing from a retirement account should always be a last resort,” she says.

______________________________________

This column was provided to The Associated Press by the personal finance site NerdWallet. The content is for educational and informational purposes and does not constitute investment advice. Liz Weston is a columnist at NerdWallet, a certified financial planner and author of “Your Credit Score.” Email: lweston@nerdwallet.com. Twitter: @lizweston.

RELATED LINK:

NerdWallet: What the new Secure 2.0 Act means for your retirement https://bit.ly/nerdwallet-secure-act
Report Error Submit a Tip

More Stories

Broadening prediction-market gambling a bad idea

Editorial 4 minute read Preview

Broadening prediction-market gambling a bad idea

Editorial 4 minute read 2:01 AM CDT

Let’s make a prediction: sooner or later, when Canadian governments find a way to take their own cut of the action, prediction-contract gambling on everything from sports to entertainment to political decisions is going to come to Canada.

And that’s a horrible, dangerous, pernicious idea.

Unless you have particular access to information — either inside information or strategic information based on skills or education — you’re not likely to make money at it. In fact, structurally, you’re likely to lose. In prediction markets, you basically pay an amount, plus fees from the company involved, to bet on whether something will or will not happen within a certain time frame. The amount you pay for your contract depends on how other people are also betting.

As Wealthsimple describes it, “You buy whichever side you think is right. Prices move with demand, so if the market leans towards one outcome, the more that side costs. If a lot of people are backing the TSX to finish above 38,000, yes gets more expensive and no gets cheaper.”

Read
2:01 AM CDT

Liz Weston: Safer ways to raid your retirement, if you have to

Liz Weston Of Nerdwallet, The Associated Press 5 minute read Preview

Liz Weston: Safer ways to raid your retirement, if you have to

Liz Weston Of Nerdwallet, The Associated Press 5 minute read Monday, Jun. 26, 2023

Raiding your retirement accounts can be expensive. Withdrawing money before age 59 1/2 typically triggers income taxes, a 10% federal penalty and — worst of all — the loss of future tax-deferred compounded returns. A 30-year-old who withdraws $1,000 from an individual retirement account or 401(k) could lose more than $11,000 in future retirement money, assuming 7% average annual returns.

In the past, there were a few ways you could avoid the penalty. Congress recently added several more, and some of those exceptions allow you to repay the money within three years. That would allow you to get a refund of the taxes you paid and — best of all — allow the money to start growing again, tax deferred, for your future.

You’re still better off leaving retirement funds alone for retirement, says Erin Itkoe, director of financial planning at Tarbox Family Office, a wealth management firm in Scottsdale, Arizona. If you can’t, though, you could at least limit the damage from taking the money out early, she says.

WHAT YOU NEED TO KNOW ABOUT SECURE 2.0

Read
Monday, Jun. 26, 2023

Gordon Bell rings in a century

Maggie Macintosh 13 minute read Preview

Gordon Bell rings in a century

Maggie Macintosh 13 minute read Updated: Yesterday at 8:06 PM CDT

Mischka Valencia had gotten used to the hum of heavy machinery at Gordon Bell High School.

“Ever since I’ve been here, it’s all been under construction,” the Grade 12 student said, standing on the sidelines of the brightly painted revamped outdoor basketball court. “I had no idea this was a court.”

The Filipina teenager landed in Winnipeg several months after the inner-city campus had transformed into a construction site.

It was the fall of 2023 and Mischka’s priorities were fitting in, befriending classmates and learning a third language via first-period French.

Read
Updated: Yesterday at 8:06 PM CDT

J’accuse!: Kinew uses French to fry interim Tory leader over alleged caucus subterfuge

Chris Kitching and Maggie Macintosh 4 minute read Preview

J’accuse!: Kinew uses French to fry interim Tory leader over alleged caucus subterfuge

Chris Kitching and Maggie Macintosh 4 minute read Thursday, Oct. 1, 2026

NDP Premier Wab Kinew took a dig at the Progressive Conservatives’ leadership change while facing off with Obby Khan’s short-term replacement for the first time in question period Thursday.

Read
Thursday, Oct. 1, 2026

Moving drama at MTYP gives voice to boy who changed law

Holly Harris 5 minute read Preview

Moving drama at MTYP gives voice to boy who changed law

Holly Harris 5 minute read 2:37 PM CDT

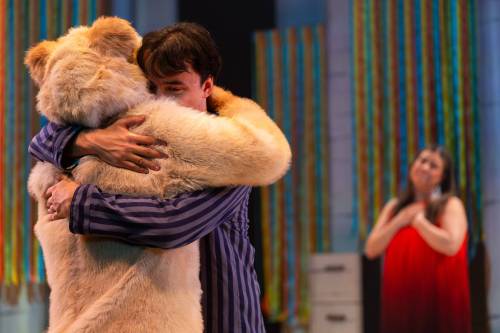
The heroic true tale of Norway House Cree Nation-born Jordan River Anderson came home Friday night, as Manitoba Theatre for Young People presented Yvette Nolan’s Jordan.

The touring production, a collaboration with Geordie Theatre, runs weekends through Oct. 11, with additional stops in Toronto, Vancouver and Ottawa’s National Arts Centre.

Having several of Anderson’s family members witness the local première underscored the evening with poignancy. Elder and Pine Creek First Nation member Barbara Nepinak added her own dignified presence and prayers following MTYP artistic director Pablo Felices-Luna’s welcoming remarks.

The season-opener also marks the Winnipeg-raised playwright’s homecoming; the Algonquin playwright, director, dramaturg, actor and educator was a fixture in our local theatre community for many years before going on to serve as artistic director for Native Earth Performing Arts from 2003 to ‘11, among other contributions.

Read
2:37 PM CDT

Health minister warns $1.2 billion in annual federal funding set to expire in March

Scott Billeck 4 minute read Preview

Health minister warns $1.2 billion in annual federal funding set to expire in March

Scott Billeck 4 minute read Thursday, Oct. 1, 2026

Manitoba’s health minister is warning of possible cuts to health care with $1.2 billion in annual funding from Ottawa set to expire next year.

“We’re very concerned that what would be the largest cut to health care in a generation is right in front of us,” Health Minister Uzoma Asagwara said Thursday at the Manitoba legislature. “It means that services that Manitobans depend on will be in jeopardy and be at risk.

“Any reductions, any cuts from Canada, will have direct impacts on the health outcomes of Manitobans.”

Asagwara, who serves as the provincial and territorial health minister lead, chaired a virtual meeting Tuesday with provincial and territorial health ministers to discuss federal funding for health care, mental health care and substance use services, which is scheduled to expire March 31, 2027.

Read
Thursday, Oct. 1, 2026