5 questions to ask when helping an older parent with money

Advertisement

Advertise with us

Conversations about money often require sensitivity and patience, especially when the person across the table is an older parent.

Read this article for free:


or

Already have an account? Log in here »

To continue reading, please subscribe:
Subscribe and receive a limited-edition Free Press branded hat or tote.

Digital Subscription

One year of digital access for only $205*

  • Enjoy unlimited reading on winnipegfreepress.com
  • Read the E-Edition, our digital replica newspaper
  • Access News Break, our award-winning app
  • Play interactive puzzles

*First annual payment billed as $205.00 + GST for one year. This annual subscription will automatically renew at $233.00 + GST every 52 weeks (10% off the regular annual price of $259.35). Offer available to new and qualified returning subscribers only. Cancel any time.

To continue reading, please subscribe:

Add Free Press access to your Brandon Sun subscription for only an additional

$1 for the first 4 weeks*

  • Enjoy unlimited reading on winnipegfreepress.com
  • Read the E-Edition, our digital replica newspaper
  • Access News Break, our award-winning app
  • Play interactive puzzles
Start now

*Your next Brandon Sun subscription payment will increase by $1.00 and you will be charged $17.95 plus GST for four weeks. After four weeks, your payment will increase to $24.95 plus GST every four weeks.

Hey there, time traveller!
This article was published 10/04/2024 (908 days ago), so information in it may no longer be current.

Conversations about money often require sensitivity and patience, especially when the person across the table is an older parent.

Some of us won’t need — or want — to get involved in someone else’s finances. But others may have to take an active role in helping an older parent manage their money. If that’s the case for you, don’t neglect a discussion about credit. Good credit matters throughout life, so any conversation you have with a parent should focus on building and maintaining healthy credit.

Here are five credit-related questions to ask older parents if you don’t know where to begin.
FILE - In this June 15, 2018, file photo, cash is fanned out from a wallet in North Andover, Mass. Conversations about money often require sensitivity and patience, especially when the person across the table is an older parent. Some of us won’t need — or want — to get involved in our parents’ finances. But others may have to take an active role in helping a parent manage their money. (AP Photo/Elise Amendola, File)

1. WHAT’S YOUR CREDIT SCORE?

Good credit scores can create opportunities and unlock lower interest rates, and they still matter even as we age. Maybe your parent wants to downsize to a new home or settle in a retirement community; having a good score can be advantageous in both scenarios.

Free credit scores are available from personal finance websites, credit card issuers and other financial institutions.

If their score is lower than they had hoped, develop a plan together for elevating it. Paying loan balances on time and using less than 30% of available credit can lift scores. Older parents with limited credit can open a secured credit card to help them build a credit history.

2. HAVE YOU REVIEWED YOUR CREDIT REPORT?

In 2023, data compromises impacted more than 350 million Americans, according to the Identity Theft Resource Center. Each data breach presents an opportunity for a bad actor to steal someone’s personal information, which can cause serious financial trouble for the victim. That’s why Liz Kishel, a certified financial planner at Modera Wealth Management in Atlanta, urges older people to examine their credit reports. The three major credit bureaus, Equifax, Experian and TransUnion, offer a free credit report every week.

Signs of identity theft or fraud include credit cards you don’t recognize, discrepancies in loan balances on the report compared with your own records, misspelled names and unfamiliar addresses.

Identity theft victims can remove fraudulent debt and information from their credit report by submitting the following to the credit bureaus:

— An identity theft report fromIdentityTheft.gov.

— Proof of identity.

— A letter listing fraudulent debts and information on the credit report. (7)

3. IS YOUR CREDIT FROZEN?

People can and do recover from identity theft or fraud, but it’s not always easy. Kishel’s advice: Freeze your credit to prevent fraud or theft from happening in the first place. When your credit is frozen, it becomes inaccessible to fraudsters who may want to open lines of credit in your name. For maximum protection, freeze your credit report with all three credit bureaus.

“A lot of (older adults) have wonderful credit scores because of the age of their credit histories,” Kishel says. “Protect the good credit that you’ve fought so hard to build.”

4. DO YOU HAVE YOUR OWN CREDIT CARD?

Older parents should have a credit account in their own name, and women may need to be especially mindful on this point. Until the Equal Credit Opportunity Act of 1974, lenders could deny loans to women without a male co-signer. As such, some older women don’t have their own credit history, leaving them financially vulnerable.

It can be difficult to distinguish the primary or the authorized user on a credit card. Parents could be joint owners, or one could be the primary owner and the other an authorized user. Call the issuer of the card if you’re not sure.

Advise the parent with authorized user status to get their own card. If the account owner dies or removes the authorized user from the card, all account activity is erased from the authorized user’s credit report. That erasure could damage the authorized user’s credit if the account was kept in pristine condition because all of that good credit history goes away.

5. HOW ARE YOU PAYING OFF CREDIT CARD DEBT?

According to the Federal Reserve Bank of New York’s February 2024 Household Debt and Credit Report, 19% of debt held by Americans ages 60-69 was credit card debt and it was 14% for those 70 and older. While many older parents live on fixed incomes, it’s still possible to get out of debt.

A payoff strategy such as the avalanche method (paying off debts in order of highest to lowest interest rate) can infuse a sense of order and progress into the debt payoff journey. Getting another credit card can help pay down debt, too. Balance transfer cards take on debts from other lenders and make it easier to pay them off because they temporarily waive interest, some for a year or more.

Older parents who want professional financial help may benefit from working with a credit counselor, who can put them on a personalized debt management plan.

To avoid getting back into debt, they may need to cut their expenses if they don’t plan to rejoin the workforce. The online database BenefitsCheckUp helps older adults find and apply for financial assistance programs to subsidize the costs of medical care and utilities, for example.

_______________________

This article was provided to The Associated Press by the personal finance website NerdWallet. Jae Bratton is a writer at NerdWallet. Email: jbratton@nerdwallet.com.

RELATED LINKS:

NerdWallet: Victim of credit card fraud? 6 actions to take now https://bit.ly/nerdwallet-credit-card-fraud

IdentityTheft.gov: https://www.identitytheft.gov/#/

BenefitsCheckUp: https://benefitscheckup.org/
Report Error Submit a Tip

More Stories

Lemonade stand brings in hundreds for West Broadway Youth Outreach

AV Kitching 9 minute read Preview

Lemonade stand brings in hundreds for West Broadway Youth Outreach

AV Kitching 9 minute read 6:00 AM CDT

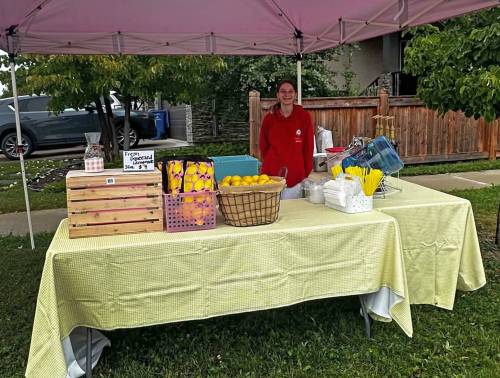
Like most 12-year-olds, there’s nothing Ruby Barkley enjoys more than a tall glass of lemonade. So when she decided to set up a lemonade stand, Ruby’s Sips + Sweets, in her neighbourhood last month, her mom was only too happy to say yes.

Especially since Ruby had decided she was going to donate proceeds of the sales to West Broadway Youth Outreach (WBYO), a non-profit organization providing recreational and life-skills programming for children aged four and up.

Ruby had set up lemonade stands in the past and was accustomed to serving up glasses from a pitchers of drink she’d already pre-made, but this time round she chose to do something different.

“We got a muddler press and I hand-pressed the lemons and then added flavours. It’s a whole process. It’s hand squeezed right before your eyes and anybody can watch it. I loved doing it,” she says.

Read
6:00 AM CDT

Broadening prediction-market gambling a bad idea

Editorial 4 minute read Preview

Broadening prediction-market gambling a bad idea

Editorial 4 minute read Saturday, Oct. 3, 2026

Let’s make a prediction: sooner or later, when Canadian governments find a way to take their own cut of the action, prediction-contract gambling on everything from sports to entertainment to political decisions is going to come to Canada.

And that’s a horrible, dangerous, pernicious idea.

Unless you have particular access to information — either inside information or strategic information based on skills or education — you’re not likely to make money at it. In fact, structurally, you’re likely to lose. In prediction markets, you basically pay an amount, plus fees from the company involved, to bet on whether something will or will not happen within a certain time frame. The amount you pay for your contract depends on how other people are also betting.

As Wealthsimple describes it, “You buy whichever side you think is right. Prices move with demand, so if the market leans towards one outcome, the more that side costs. If a lot of people are backing the TSX to finish above 38,000, yes gets more expensive and no gets cheaper.”

Read
Saturday, Oct. 3, 2026

5 questions to ask when helping an older parent with money

Jae Bratton Of Nerdwallet, The Associated Press 6 minute read Preview

5 questions to ask when helping an older parent with money

Jae Bratton Of Nerdwallet, The Associated Press 6 minute read Wednesday, Apr. 10, 2024

Conversations about money often require sensitivity and patience, especially when the person across the table is an older parent.

Some of us won’t need — or want — to get involved in someone else’s finances. But others may have to take an active role in helping an older parent manage their money. If that’s the case for you, don’t neglect a discussion about credit. Good credit matters throughout life, so any conversation you have with a parent should focus on building and maintaining healthy credit.

Here are five credit-related questions to ask older parents if you don’t know where to begin.

1. WHAT’S YOUR CREDIT SCORE?

Read
Wednesday, Apr. 10, 2024

Record participation, funds raised in 2026 breast cancer awareness race

Maggie Macintosh 4 minute read Preview

Record participation, funds raised in 2026 breast cancer awareness race

Maggie Macintosh 4 minute read Updated: Yesterday at 7:08 PM CDT

It’s become a tradition for the West End Legends to gather, get dressed up in hot pink and gab about their late girlfriend on the first Sunday of Breast Cancer Awareness Month.

“Mary was a beauty, a brain, an athlete and a friend,” said Linda Opalko, a 67-year-old member of the fundraising team founded in honour of Mary Stawychny.

Stawychny’s last breath was taken the same day the group — made up of friends the career teacher maintained since she grew up on Ingersoll Street more than 50 years ago — got together for the 2022 CIBC Run for the Cure.

“We were walking as she was leaving us four years ago,” Opalko said as she and fellow fundraisers strolled down Wellington Crescent on Sunday morning.

Read
Updated: Yesterday at 7:08 PM CDT

Board game company charts winning path

Aaron Epp 5 minute read Preview

Board game company charts winning path

Aaron Epp 5 minute read Friday, Oct. 2, 2026

Dennis Northcott has launched a game without frontiers.

The Winnipeg entrepreneur is the co-designer of Galactic Cruise, a board game published last year by Kinson Key Games LLC, the business he co-founded. Since its release, Galactic Cruise has been translated into 11 languages and sold around 50,000 copies worldwide.

It’s also one of three finalists for this year’s Deutsche Spiele Preis, a prestigious community-voted board game award. Northcott will travel to Essen, Germany, later this month, where the winner will be announced at Spiel Essen, an annual board game trade fair.

“It’s been amazing,” Northcott said of the response to Galactic Cruise during an interview in his Island Lakes neighbourhood home earlier this week. “The sales have been great, but it’s also been amazing in terms of people giving their reviews.”

Read
Friday, Oct. 2, 2026

Fentanyl, crack seized in traffic stop

1 minute read Yesterday at 12:13 PM CDT

Winnipeg police seized fentanyl and arrested three people after pulling over a vehicle with a smashed windshield in the city's north end Friday.

The incident happened at about 8:30 a.m. Oct. 2 on Powers Street near Flora Avenue. While they were speaking with the vehicle's occupants, police officers saw a weapon "in plain view," the Winnipeg Police Service stated in a news release Sunday.

Officers searched the vehicle, finding a machete, plastic brass knuckles with a functioning Taser, 73 grams of fentanyl worth about $3,725 nine grams of cocaine worth about $720, 13 grams of crack cocaine worth about $1,000, prescription pills, cell phones, scales and packaging materials, and $790 in cash.

Anthony Courchene, 41, is charged with seven weapons, drug trafficking and proceeds of crime-related offences. He was also arrested on two Powerview RCMP warrants related to assault and release order compliance charges.